Business & commercial
Commercial property finance, considered end to end.
Commercial property lending is assessed on the property, the lease and the business behind it. We look at the whole picture and approach lenders whose appetite matches your asset.
Client reviews
- “made the whole process easy”Lahari K · Google ·
- “incredibly easy and stress-free”Laura Rossi · Google ·
- “incredibly responsive, hardworking”Martin V · Google ·
- “cannot speak highly enough of the team”Jake Frei · Google ·
- “working with Tharun for years”Vidhu Shekhar · Google ·
- “supported and genuinely cared for”Andrea Veltom · Google ·
- “seamless from start to finish”John Z · Google ·
- “made the whole process incredibly easy”Kevin Fernandopulle · Google ·
- “a much better interest rate”Bradley L · Google ·
- “Great communication, great outcome”Charles-emile · Google ·
- “Best in the business!”Saba Khan · Google ·
- “an amazing advisor, fast, efficient”harold quek · Google ·
- “seamless and stress free”Victor Zhou · Google ·
- “incredibly professional and responsive”steven wu · Google ·
- “went above and beyond”Jennifer Kim · Google ·
- “I genuinely cannot recommend him enough”David Maxwell · Google ·
- “I wouldn’t have done this without him”Phaedra McGhie · Google ·
Our approach
We present your commercial purchase the way lenders assess it, and secure finance aligned with your investment or business strategy.
Who this suits
- 1. Business owners buying their premises
- 2. Investors buying leased commercial property
- 3. Owners of office, retail or industrial assets
- 4. Borrowers refinancing commercial debt
- 5. Buyers of mixed-use properties
Talk it through with a director. A 20-minute strategy call, free and with no obligation.
Leveraging over 50 lending partners to achieve these results for you
From the major banks to specialist lenders, we compare policy and pricing to find the loan that fits.
- Bank of Queensland
- Capital Finance
- HSBC
- Medfin
- NWC Finance
- Paramount Residential
- Suncorp
How commercial property lending differs
Commercial property loans are assessed differently from residential loans. Lenders look closely at the property type, location, condition and how easily it could be re-leased or sold. Offices, retail, industrial, medical and specialised assets such as childcare centres or hospitality venues each carry a different risk view, and some lenders avoid certain categories altogether.
Loan terms are usually shorter than for residential lending, and facilities may be reviewed periodically. Pricing is often negotiated rather than taken from a rate card, and it reflects the strength of the borrower, the lease and the security. Knowing which lenders are actively lending on your asset type is where a broker adds real value.
- Offices and professional suites
- Retail shops and strip centres
- Warehouses and industrial units
- Medical and specialised premises
- Mixed-use buildings
Leases, financials and serviceability
For an investment property, the lease is central. Lenders review the tenant's quality, the remaining lease term, rent reviews and who pays outgoings. A strong tenant on a long lease is viewed very differently from a vacant property or a short tenancy. Lenders also commonly test interest cover – whether the net rent comfortably covers the interest.
For premises your business will occupy, the assessment focuses on the business's financials – tax returns, financial statements, management accounts and existing debt – alongside the security. We prepare a clear credit submission that explains the business, the property and the purpose, because commercial credit teams exercise judgement and context matters.
- Lease terms, tenant quality and remaining term
- Net rental income against interest
- Business financial statements and tax returns
- Property valuation and saleability
Talk it through with a director. A 20-minute strategy call, free and with no obligation.
Structuring commercial facilities
Commercial loans can be set up as principal and interest term loans, interest-only facilities or a combination, and may be held by a company, trust or individuals. The borrowing entity, guarantors and any additional security all need to be settled upfront. Some facilities include covenants, such as minimum interest cover or regular financial reporting, and breaching them can give the lender the right to review the loan.
We read the terms carefully with you and highlight the conditions that matter. Where you hold other property, we consider whether to keep securities separate so one asset is not tied to another. We work with your accountant and solicitor on the entity and documents.
Costs to plan for in a commercial purchase
Commercial purchases carry stamp duty, legal fees and due diligence costs such as building reports and zoning or environmental checks. Lenders typically charge establishment fees and commercial valuation fees, which are generally higher than residential ones, and sometimes ongoing facility or review fees.
GST can apply to commercial property purchases unless, for example, the sale qualifies as a going concern, and this affects how much cash you need at settlement. Your accountant should confirm the GST position. We include all lending costs in our comparison and flag timing issues, such as when valuations and approvals are needed relative to the contract's finance date.
- Stamp duty and legal fees
- Commercial valuation and establishment fees
- GST, depending on the transaction
- Building, zoning and environmental checks
Let’s take the next steps in your finance journey
One director from first call to settlement, and still here afterwards. A strategy call is free, takes 20 minutes and comes with no obligation.
Stage 1
Deal review
We review the property, lease, contract and your business or investment position, and gauge which lenders are likely to have appetite.
Stage 2
Submission
We prepare a credit submission with financials, lease details and context, and approach suitable lenders for indicative terms.
Stage 3
Terms compared
We compare indicative offers on pricing, term, covenants, fees and security, and explain the trade-offs before you choose.
Stage 4
Approval to settlement
We manage valuation, formal approval and documentation, working with your solicitor and accountant to meet contract deadlines.
Stage 5
Facility reviews
After settlement we track review dates and lease changes, and approach lenders early when a refinance or restructure is worth considering.
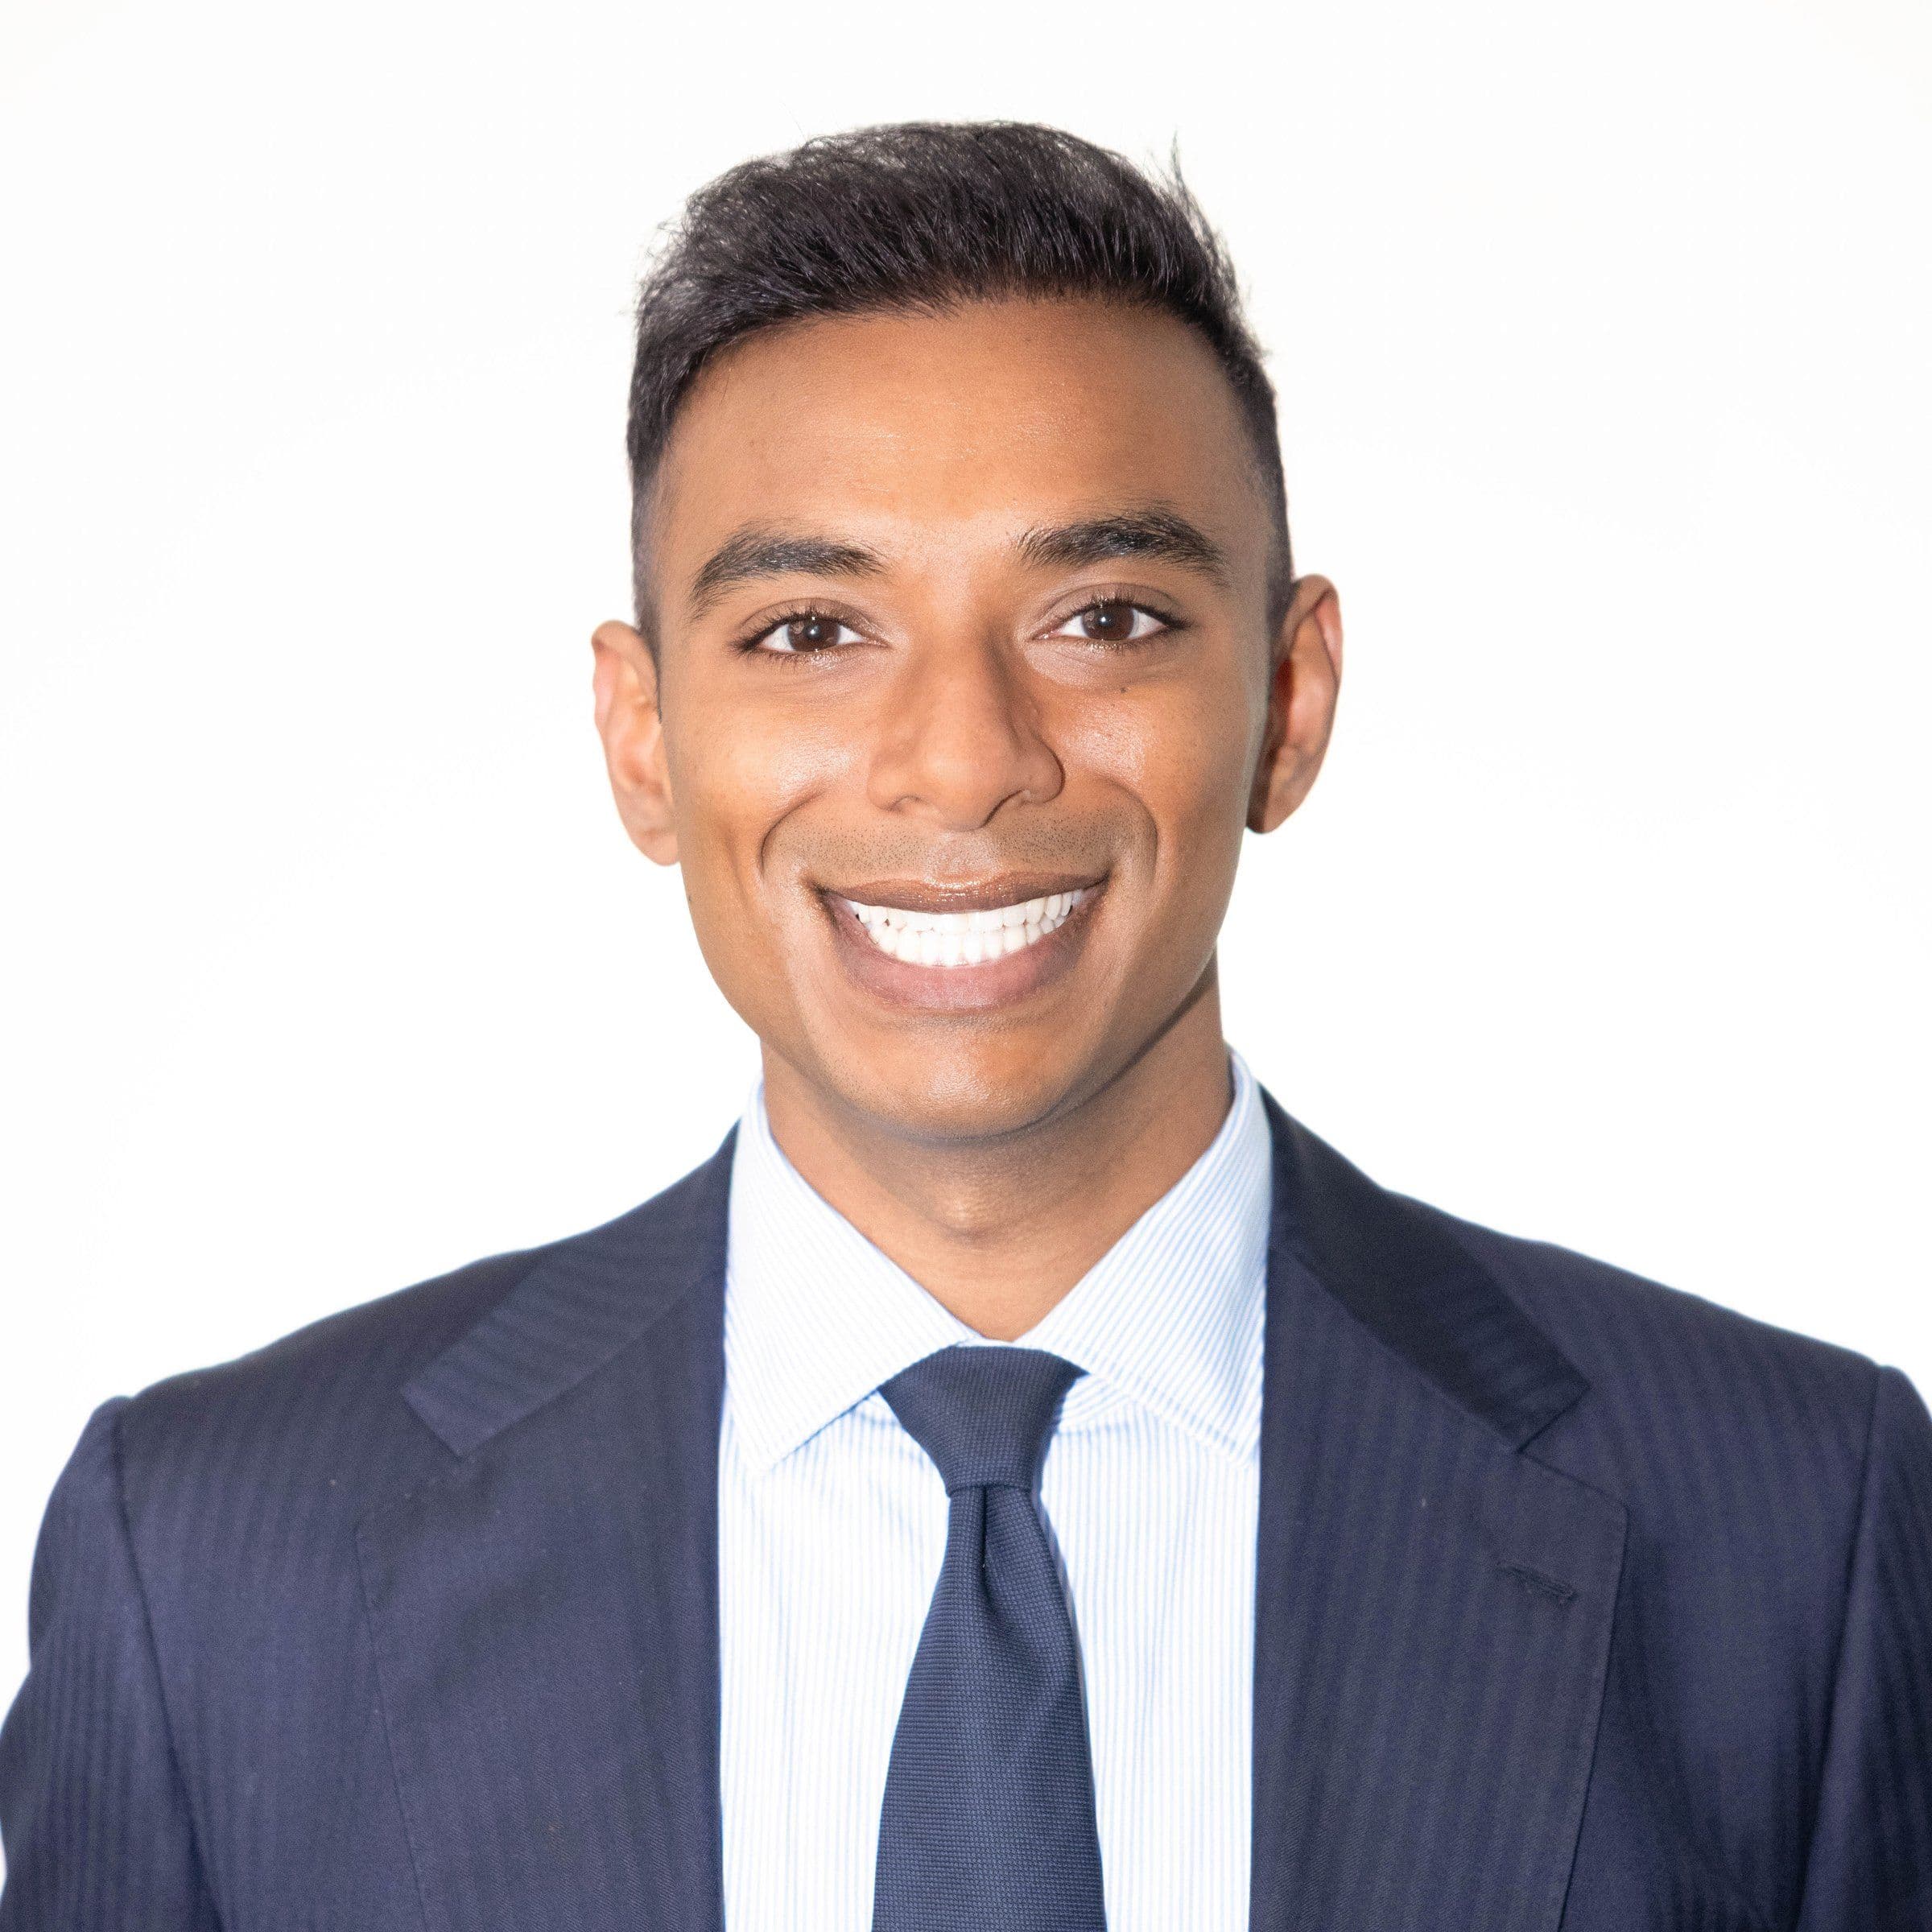
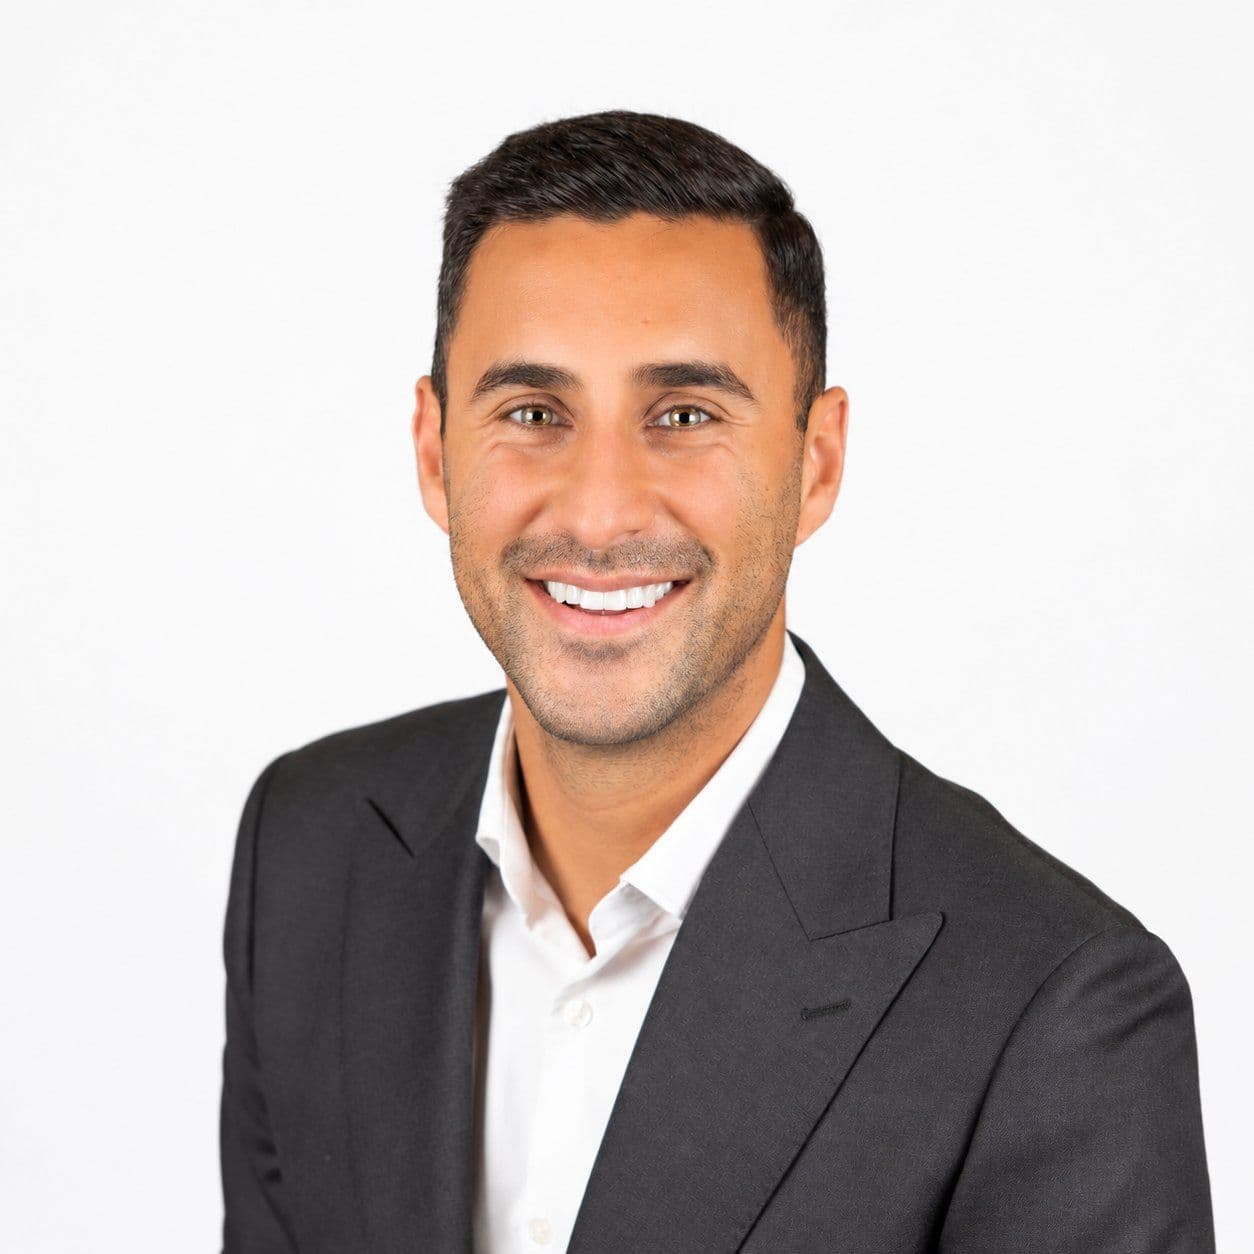
Speak with Tharun or Zain
Things to weigh up
Vacancy changes the picture
A vacant property or a lease nearing expiry can limit lender options or reduce how much they will lend. Factor lease timing into your plans.
Valuations take longer
Commercial valuations are more detailed than residential ones. Allow for this when negotiating the finance date in your contract.
Covenants and periodic reviews
Some facilities require ongoing financial reporting and can be reviewed by the lender. Understand the conditions before you sign.
Specialised assets narrow the field
Childcare, hospitality, rural or special-use properties suit fewer lenders. Engaging lenders early helps avoid surprises late in the process.
Run the numbers
Weekly, fortnightly or monthly repayments, principal & interest or interest-only.
Monthly repayment
$3,935
- Total interest
- $766,517
- Total repaid
- $1,416,517
Estimate only. Not an offer or approval of credit. Every lender assesses differently.
Questions commercial property buyers typically ask
Can I use my home as security for a commercial purchase?
Some lenders will lend against commercial property with residential property as additional security, which can broaden options or improve terms. The trade-off is that your home becomes tied to the commercial loan. We weigh this with you before recommending a structure.
Do I need a full set of financial statements?
For most commercial lending, yes. Lenders generally want recent tax returns and financial statements for the borrowing entity and any guarantors, plus management accounts if the latest year is not finalised. Some lenders offer reduced-documentation options, usually on stricter terms. We tell you exactly what each lender needs.
What is the difference between a commercial loan and development finance?
A commercial loan funds the purchase or refinance of an existing property. Development finance funds a construction project, typically with staged drawdowns, presale requirements and a different assessment approach. If your plans include significant building works, we discuss which category applies and the lenders suited to it.
What does a mortgage broker cost me?
In most cases, nothing. Lenders pay us a commission when your loan settles, and we disclose it in full in your Credit Proposal before you proceed. If a fee ever applies to your scenario, we tell you upfront, in writing.
You may also be considering
All services- Home LoansWe support clients through every stage of the purchase process, structuring lending solutions for owner-occupiers with a tailored, strategic approach.
- Investment LoansWe structure investment lending with the long game in mind – the right lender, the right structure and room to keep building.
- First Home BuyersWe guide first home buyers through the entire home buying journey, from understanding borrowing capacity to accessing what government schemes they may be eligible for. We work with you during this pivotal period in your life to make your entry into the property market as clear and achievable as possible.
Let’s map out your next move
Tell us where you are and where you want to be. A director will come back to you within one business day.
- Tharun Rameshbabu
- 0493 125 004tharun@terrainfp.com
- Zain Sumar
- 0494 503 777zain@terrainfp.com
- Office
- Level 3, 55 Pyrmont Bridge Road, Pyrmont NSW 2009