Invest
Lending structured for this property and the next.
Investment lending is about more than one rate on one property. We structure each loan so your portfolio stays flexible and your borrowing capacity is protected for what comes next.
Client reviews
- “made the whole process easy”Lahari K · Google ·
- “incredibly easy and stress-free”Laura Rossi · Google ·
- “incredibly responsive, hardworking”Martin V · Google ·
- “cannot speak highly enough of the team”Jake Frei · Google ·
- “working with Tharun for years”Vidhu Shekhar · Google ·
- “supported and genuinely cared for”Andrea Veltom · Google ·
- “seamless from start to finish”John Z · Google ·
- “made the whole process incredibly easy”Kevin Fernandopulle · Google ·
- “a much better interest rate”Bradley L · Google ·
- “Great communication, great outcome”Charles-emile · Google ·
- “Best in the business!”Saba Khan · Google ·
- “an amazing advisor, fast, efficient”harold quek · Google ·
- “seamless and stress free”Victor Zhou · Google ·
- “incredibly professional and responsive”steven wu · Google ·
- “went above and beyond”Jennifer Kim · Google ·
- “I genuinely cannot recommend him enough”David Maxwell · Google ·
- “I wouldn’t have done this without him”Phaedra McGhie · Google ·
Our approach
We structure your investment lending to protect your borrowing capacity and keep each property working toward the portfolio you want to build.
Who this suits
- 1. First-time property investors
- 2. Homeowners using equity to invest
- 3. Investors building a multi-property portfolio
- 4. Buyers purchasing through a trust or company
- 5. Investors reviewing an existing structure
- 6. Owners converting a home into a rental
Talk it through with a director. A 20-minute strategy call, free and with no obligation.
Leveraging over 50 lending partners to achieve these results for you
From the major banks to specialist lenders, we compare policy and pricing to find the loan that fits.
- Bank of Queensland
- Capital Finance
- HSBC
- Medfin
- NWC Finance
- Paramount Residential
- Suncorp
How lenders assess investment lending
Lenders assess investment loans differently from owner-occupier loans. They count only part of the expected rental income, to allow for vacancies and costs, and test all your debts at an assessment rate above the actual rate. Each additional property changes the calculation, so the order and lender you choose for each purchase can affect how far your capacity stretches.
Pricing differs too. Investment loans are often priced above owner-occupier loans, and interest-only repayments are usually priced higher again. Some lenders also take a more favourable view of tax benefits when assessing serviceability than others. Understanding these differences across more than 50 lenders is central to how TFP plans an investment purchase.
- Rental income shaded for vacancy and costs
- All existing debts tested at a buffer
- Property type and location restrictions
- Policy on trust and company borrowers
Avoiding cross-collateralisation and keeping control
Cross-collateralisation happens when one loan is secured by more than one property, or one property secures several loans. Lenders sometimes set it up by default because it gives them more control. For investors, it can make selling a property, refinancing or moving to another lender harder, because the lender may revalue every property involved before releasing one.
We generally prefer standalone security, where each loan is secured only by its own property, with any equity release for deposits set up as a separate loan against your home. This keeps each property independent, makes future refinancing simpler and gives you more choice about which lender holds which loan as the portfolio grows.
Talk it through with a director. A 20-minute strategy call, free and with no obligation.
Interest-only, offset and loan splits
Many investors use interest-only repayments for a period to manage cash flow, particularly while they still owe money on their own home. Interest-only periods end, and repayments rise when the loan reverts to principal and interest, so we plan for that from the start rather than when the letter arrives.
Separating loans by purpose is just as important. Mixing personal and investment borrowing in one loan can complicate which interest is deductible. Placing offset accounts deliberately and keeping clean splits for each purpose help keep records clear. We structure the lending; your accountant advises on the tax treatment.
- Separate splits for each borrowing purpose
- Interest-only periods planned with an exit
- Offset placement aligned with your strategy
- Clean records for your accountant
Costs and buffers investors should plan for
Investment purchases carry the usual costs – stamp duty, legal fees, inspections and lender fees – plus some specific to investors. Land tax may apply depending on your total holdings, and NSW applies additional duties and surcharges in some cases, such as for foreign purchasers. Property management fees, landlord insurance, strata levies and maintenance all reduce the net return.
We encourage investors to hold a cash buffer for vacancies, rate changes and repairs. An offset account or available redraw can hold that buffer while still reducing interest. Planning for these costs upfront makes the next purchase easier to fund and easier for a lender to assess.
- Stamp duty and any applicable surcharges
- Land tax, where thresholds are exceeded
- Landlord insurance and strata levies
- Property management and maintenance
Let’s take the next steps in your finance journey
One director from first call to settlement, and still here afterwards. A strategy call is free, takes 20 minutes and comes with no obligation.
Stage 1
Strategy call
We discuss your goals, existing properties and debts, and how this purchase fits into your longer-term plan.
Stage 2
Capacity planning
We model borrowing capacity across lenders and plan which lender should hold this loan to preserve options for future purchases.
Stage 3
Structure design
We design loan splits, security arrangements and any equity release, avoiding cross-collateralisation where that suits you.
Stage 4
Approval to settlement
We manage the application, valuation and settlement, coordinating with your conveyancer, accountant and property manager where needed.
Stage 5
Portfolio reviews
After settlement we review your portfolio periodically, including rates, interest-only expiries and opportunities to restructure or refinance.
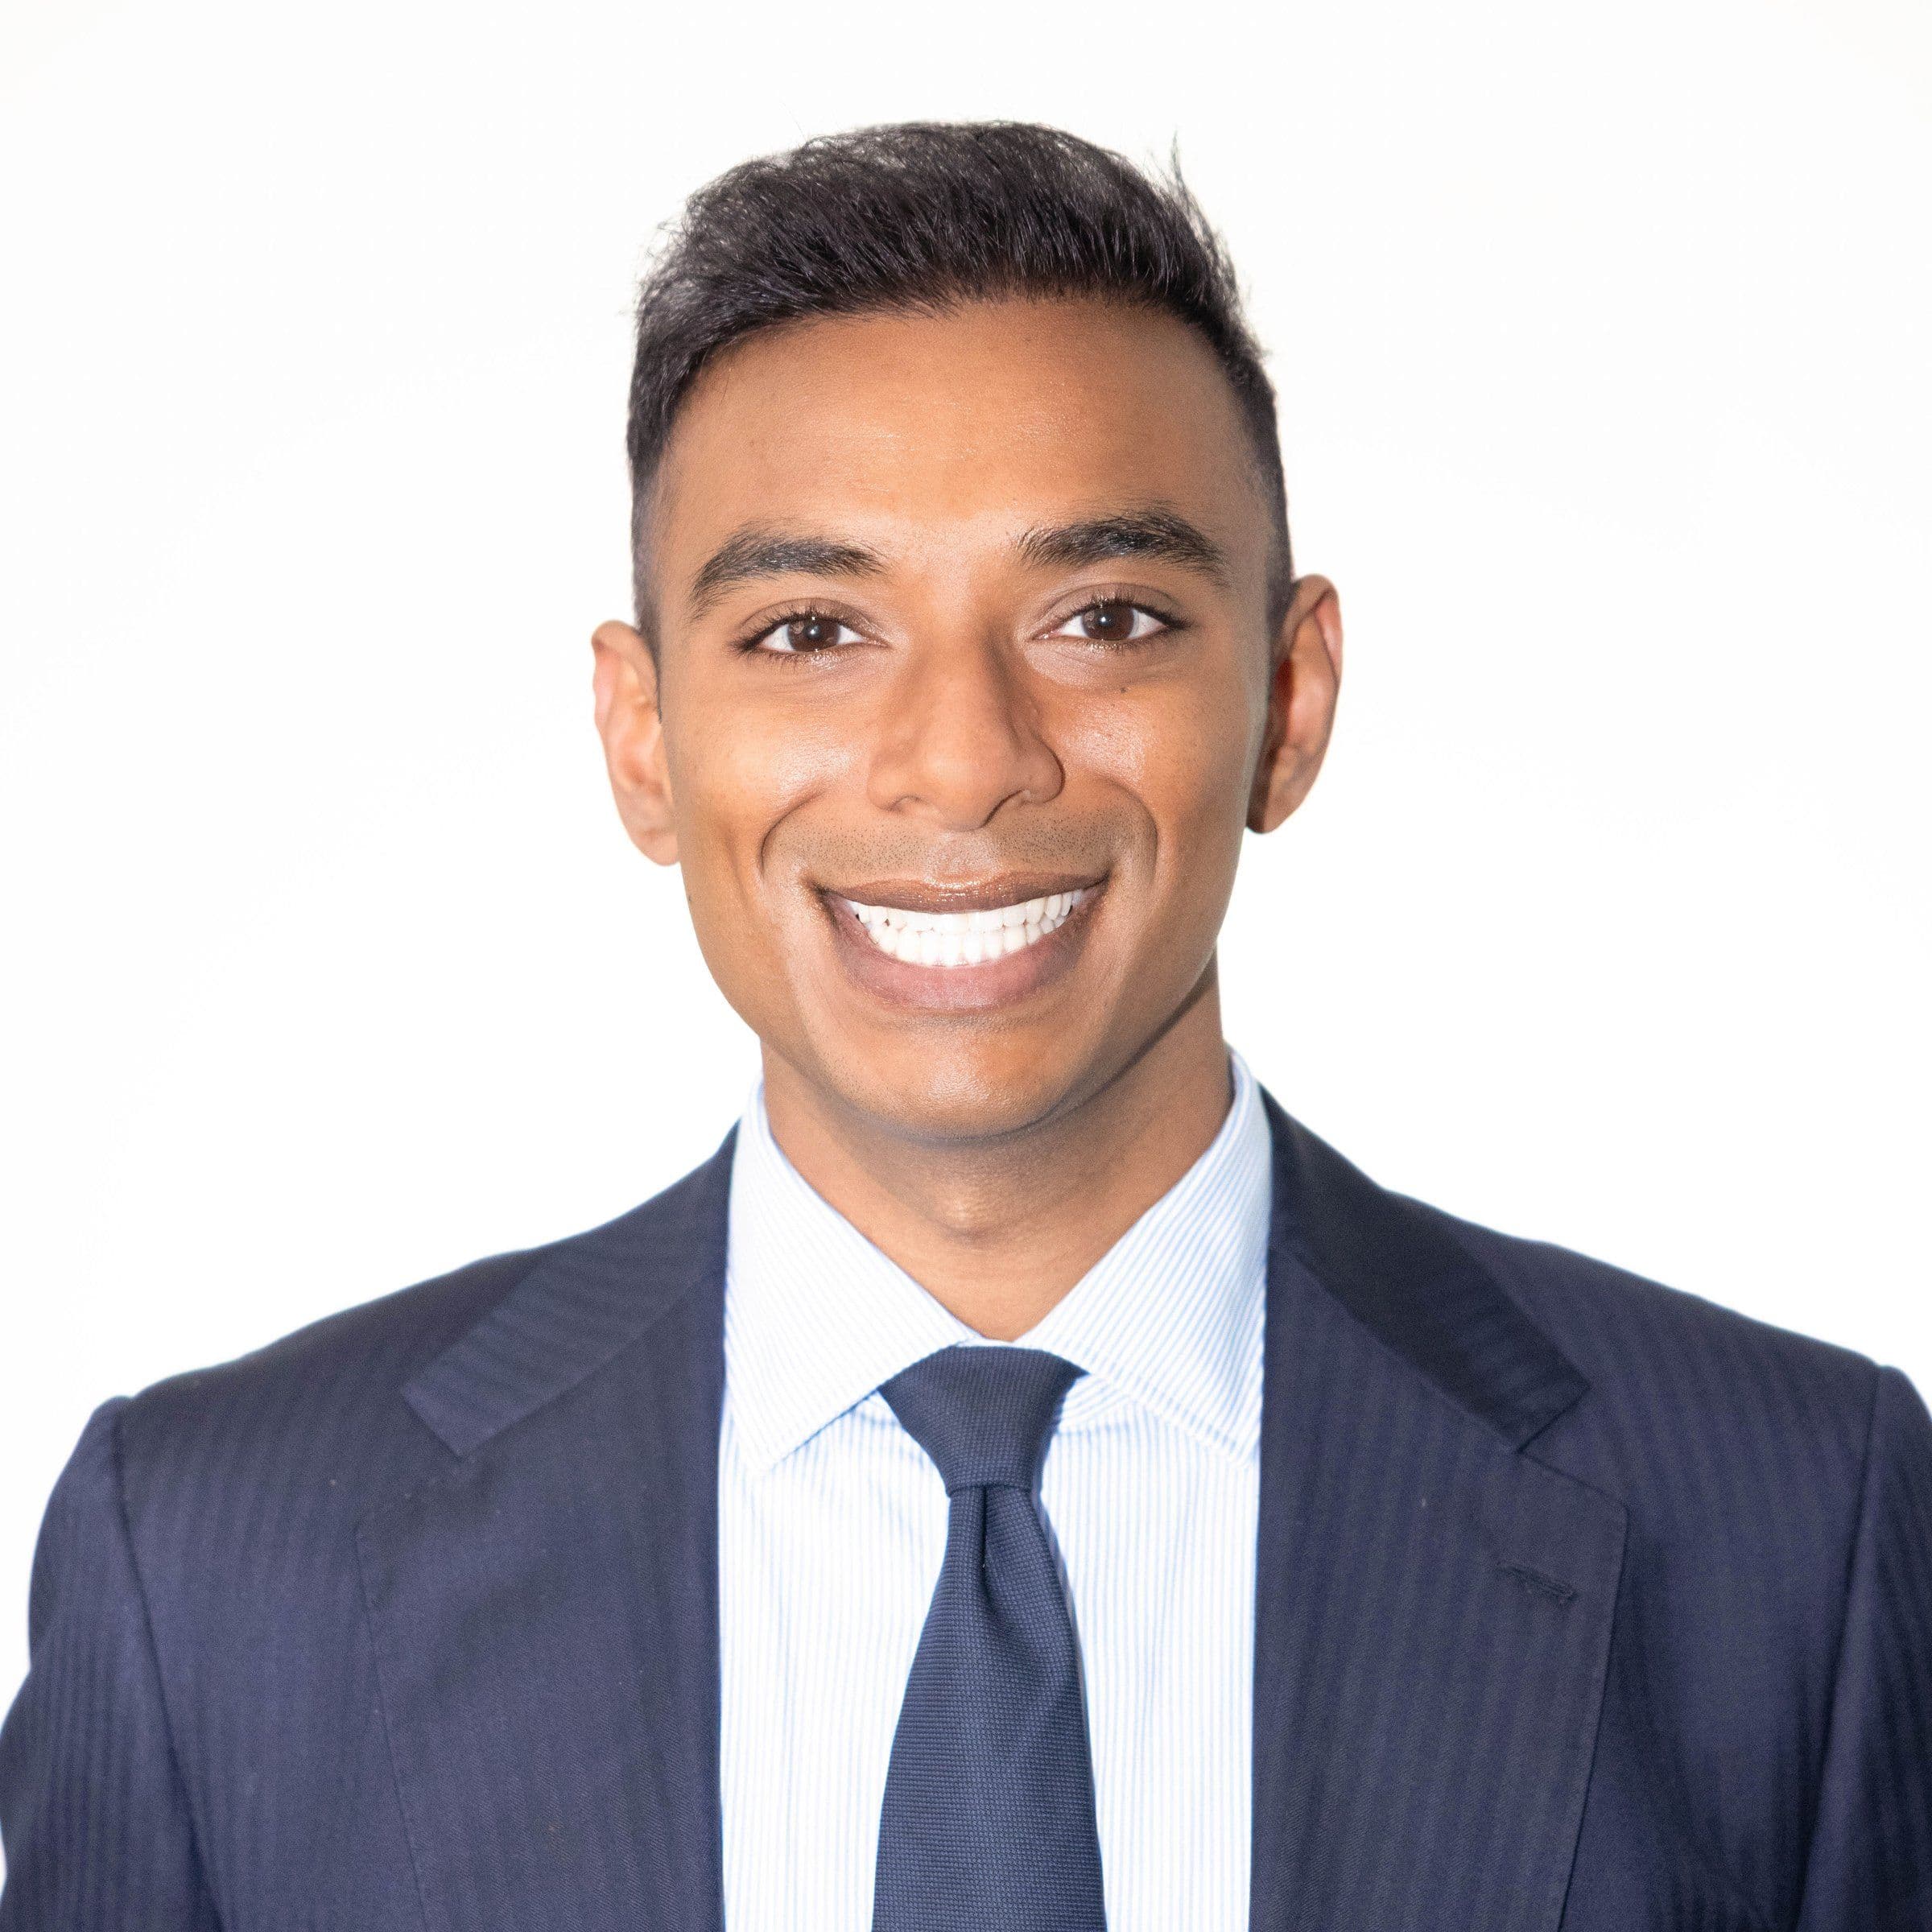
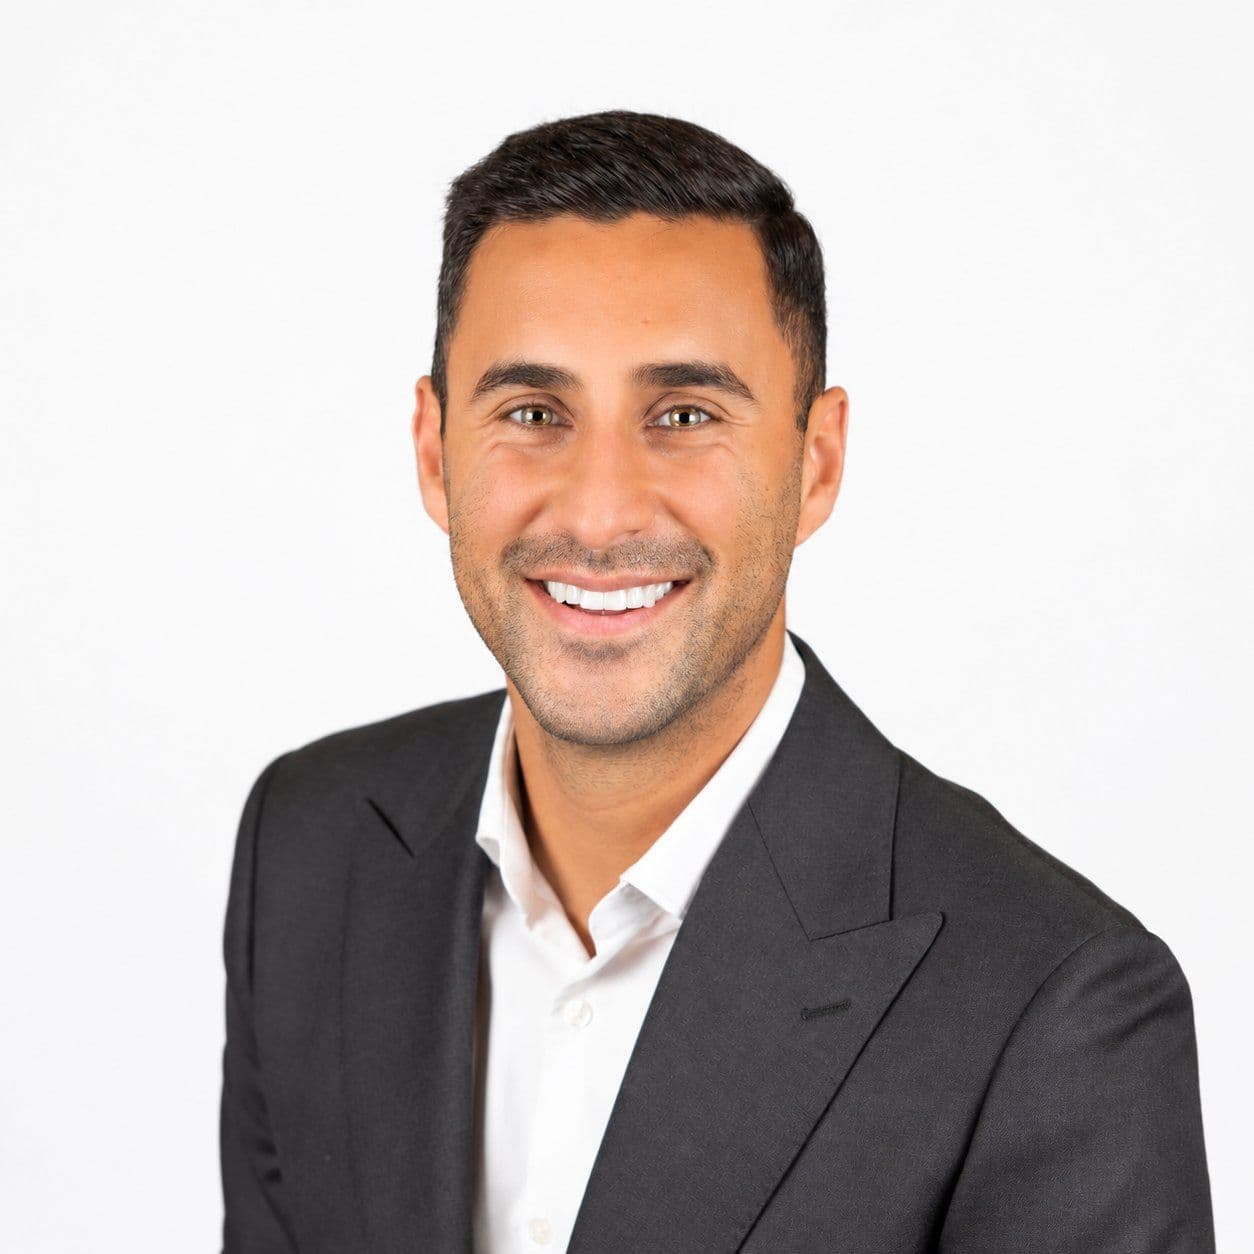
Speak with Tharun or Zain
Things to weigh up
Default cross-collateralisation
Some lenders link securities automatically when you borrow against your home for a deposit. Ask how the security will be held before you sign.
Interest-only periods end
When an interest-only period ends, repayments increase and an extension is not guaranteed. The lender reassesses at that point under its current policy.
Mixing loan purposes
Redrawing from an investment loan for personal spending can complicate deductibility. Keep separate splits and speak with your accountant.
Lender exposure limits
Some lenders limit total exposure to one borrower or tighten policy for larger portfolios. Spreading loans across lenders can preserve future capacity.
Run the numbers
Gross and net yield, and what an investment property costs you each week.
Weekly cash flow after tax
−$171/wk
Negatively geared (estimate)
- Gross yield
- 4.53%
- Net yield
- 3.22%
- Cash flow before tax
- −$272/wk
Estimate only. Not an offer or approval of credit. Every lender assesses differently.
Questions property investors typically ask
Can I use equity in my home to buy an investment property?
Often, yes. Where your home has risen in value or your loan has reduced, a lender may let you borrow against that equity for the deposit and costs. We usually set this up as a separate loan split secured by your home, so its purpose is clear and the investment loan stands on its own security.
Should I buy in my personal name or through a trust?
Ownership structure affects tax, asset protection and lending options, so it is a question for your accountant and solicitor first. Lending to trusts and companies is available, but fewer lenders offer it and policy varies. Once the structure is decided, we find a lender that suits it.
Does rental income count fully toward my borrowing capacity?
No. Lenders generally include only a portion of rental income to allow for vacancy, management and other costs, and that portion varies between lenders. This is one reason borrowing capacity can differ considerably from one lender to the next.
What does a mortgage broker cost me?
In most cases, nothing. Lenders pay us a commission when your loan settles, and we disclose it in full in your Credit Proposal before you proceed. If a fee ever applies to your scenario, we tell you upfront, in writing.
You may also be considering
All services- RefinancingWe review and restructure existing lending to secure more competitive rates, unlock equity, or consolidate debt – ensuring your finance continues to work in your favour.
- SMSF LendingWe help clients invest in property through their superannuation, structuring SMSF lending in line with long-term wealth and retirement objectives.
- Home LoansWe support clients through every stage of the purchase process, structuring lending solutions for owner-occupiers with a tailored, strategic approach.
Let’s map out your next move
Tell us where you are and where you want to be. A director will come back to you within one business day.
- Tharun Rameshbabu
- 0493 125 004tharun@terrainfp.com
- Zain Sumar
- 0494 503 777zain@terrainfp.com
- Office
- Level 3, 55 Pyrmont Bridge Road, Pyrmont NSW 2009