Buy a home
Lending that keeps pace with your build.
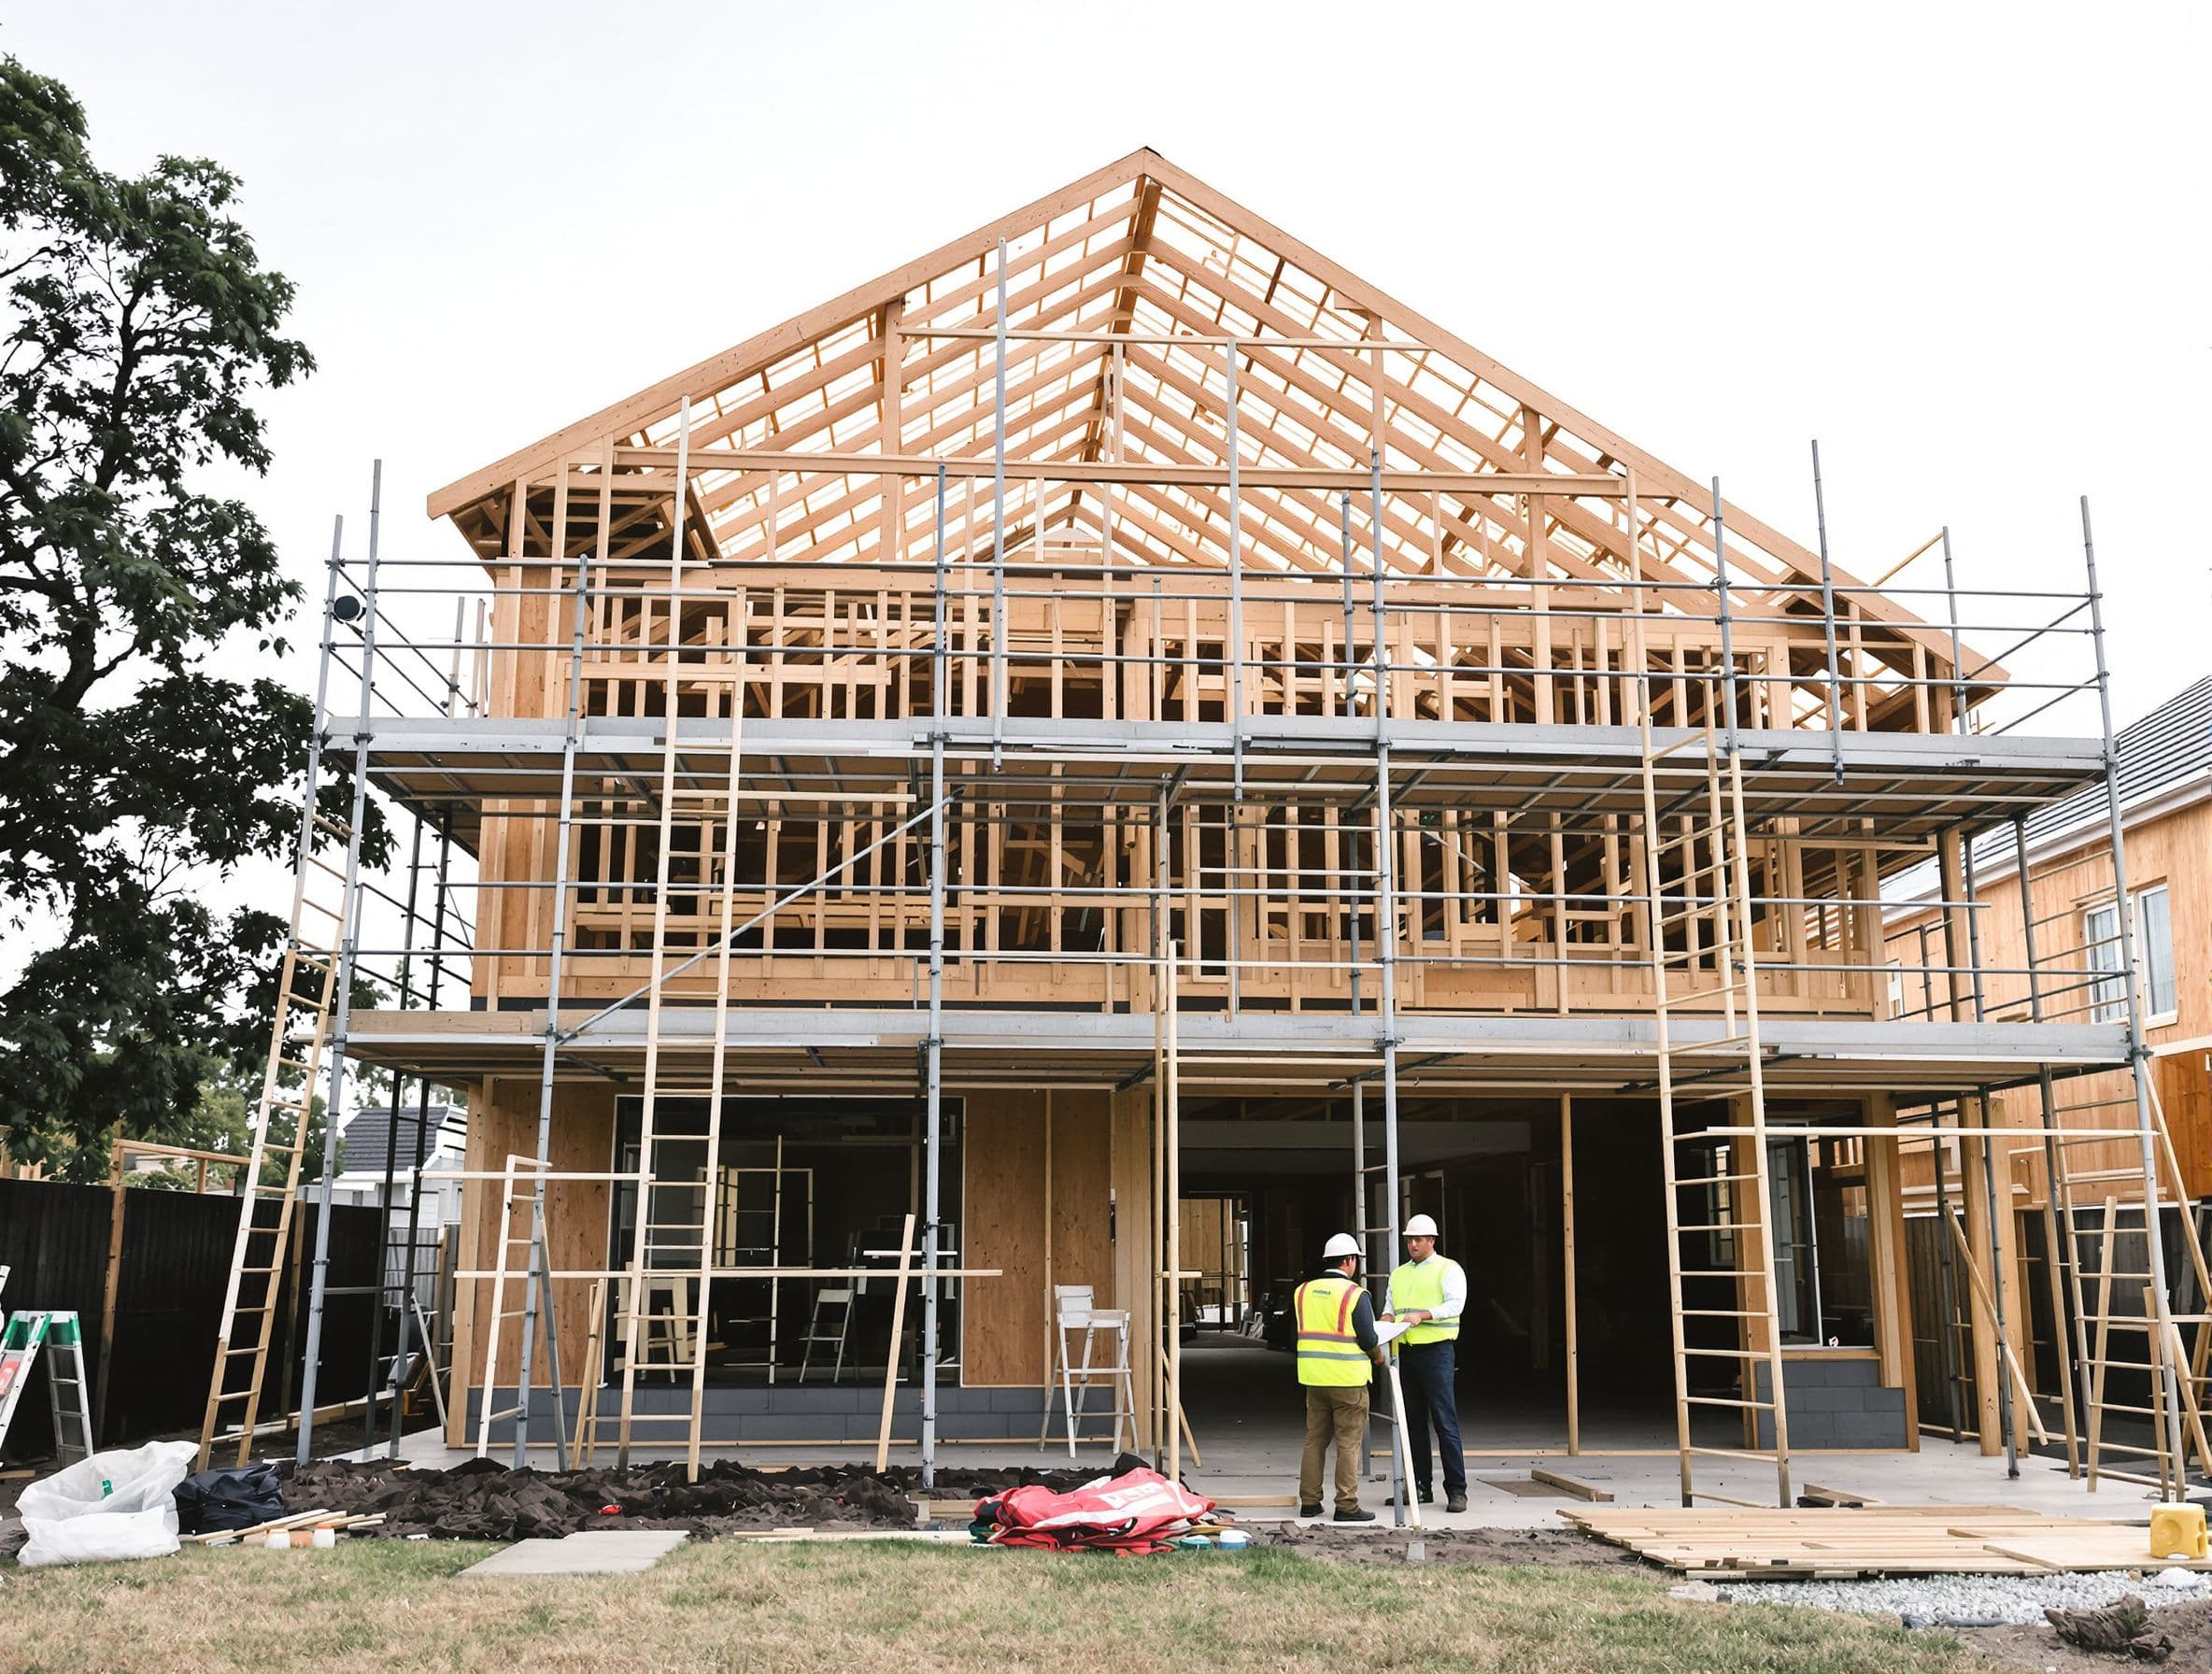
Building, or knocking down and rebuilding, needs lending that releases funds as the work progresses. We structure construction finance around your contract, your builder and your project.
Client reviews
- “made the whole process easy”Lahari K · Google ·
- “incredibly easy and stress-free”Laura Rossi · Google ·
- “incredibly responsive, hardworking”Martin V · Google ·
- “cannot speak highly enough of the team”Jake Frei · Google ·
- “working with Tharun for years”Vidhu Shekhar · Google ·
- “supported and genuinely cared for”Andrea Veltom · Google ·
- “seamless from start to finish”John Z · Google ·
- “made the whole process incredibly easy”Kevin Fernandopulle · Google ·
- “a much better interest rate”Bradley L · Google ·
- “Great communication, great outcome”Charles-emile · Google ·
- “Best in the business!”Saba Khan · Google ·
- “an amazing advisor, fast, efficient”harold quek · Google ·
- “seamless and stress free”Victor Zhou · Google ·
- “incredibly professional and responsive”steven wu · Google ·
- “went above and beyond”Jennifer Kim · Google ·
- “I genuinely cannot recommend him enough”David Maxwell · Google ·
- “I wouldn’t have done this without him”Phaedra McGhie · Google ·
Our approach
We arrange lending that matches your build, from the first progress payment to completion, so your finance keeps pace with the project.
Who this suits
- 1. Owners building a new home
- 2. Knockdown-rebuild projects
- 3. Buyers of house-and-land packages
- 4. Homeowners planning major renovations
- 5. Investors building a duplex
Talk it through with a director. A 20-minute strategy call, free and with no obligation.
Leveraging over 50 lending partners to achieve these results for you
From the major banks to specialist lenders, we compare policy and pricing to find the loan that fits.
- Bank of Queensland
- Capital Finance
- HSBC
- Medfin
- NWC Finance
- Paramount Residential
- Suncorp
Funds released as you build
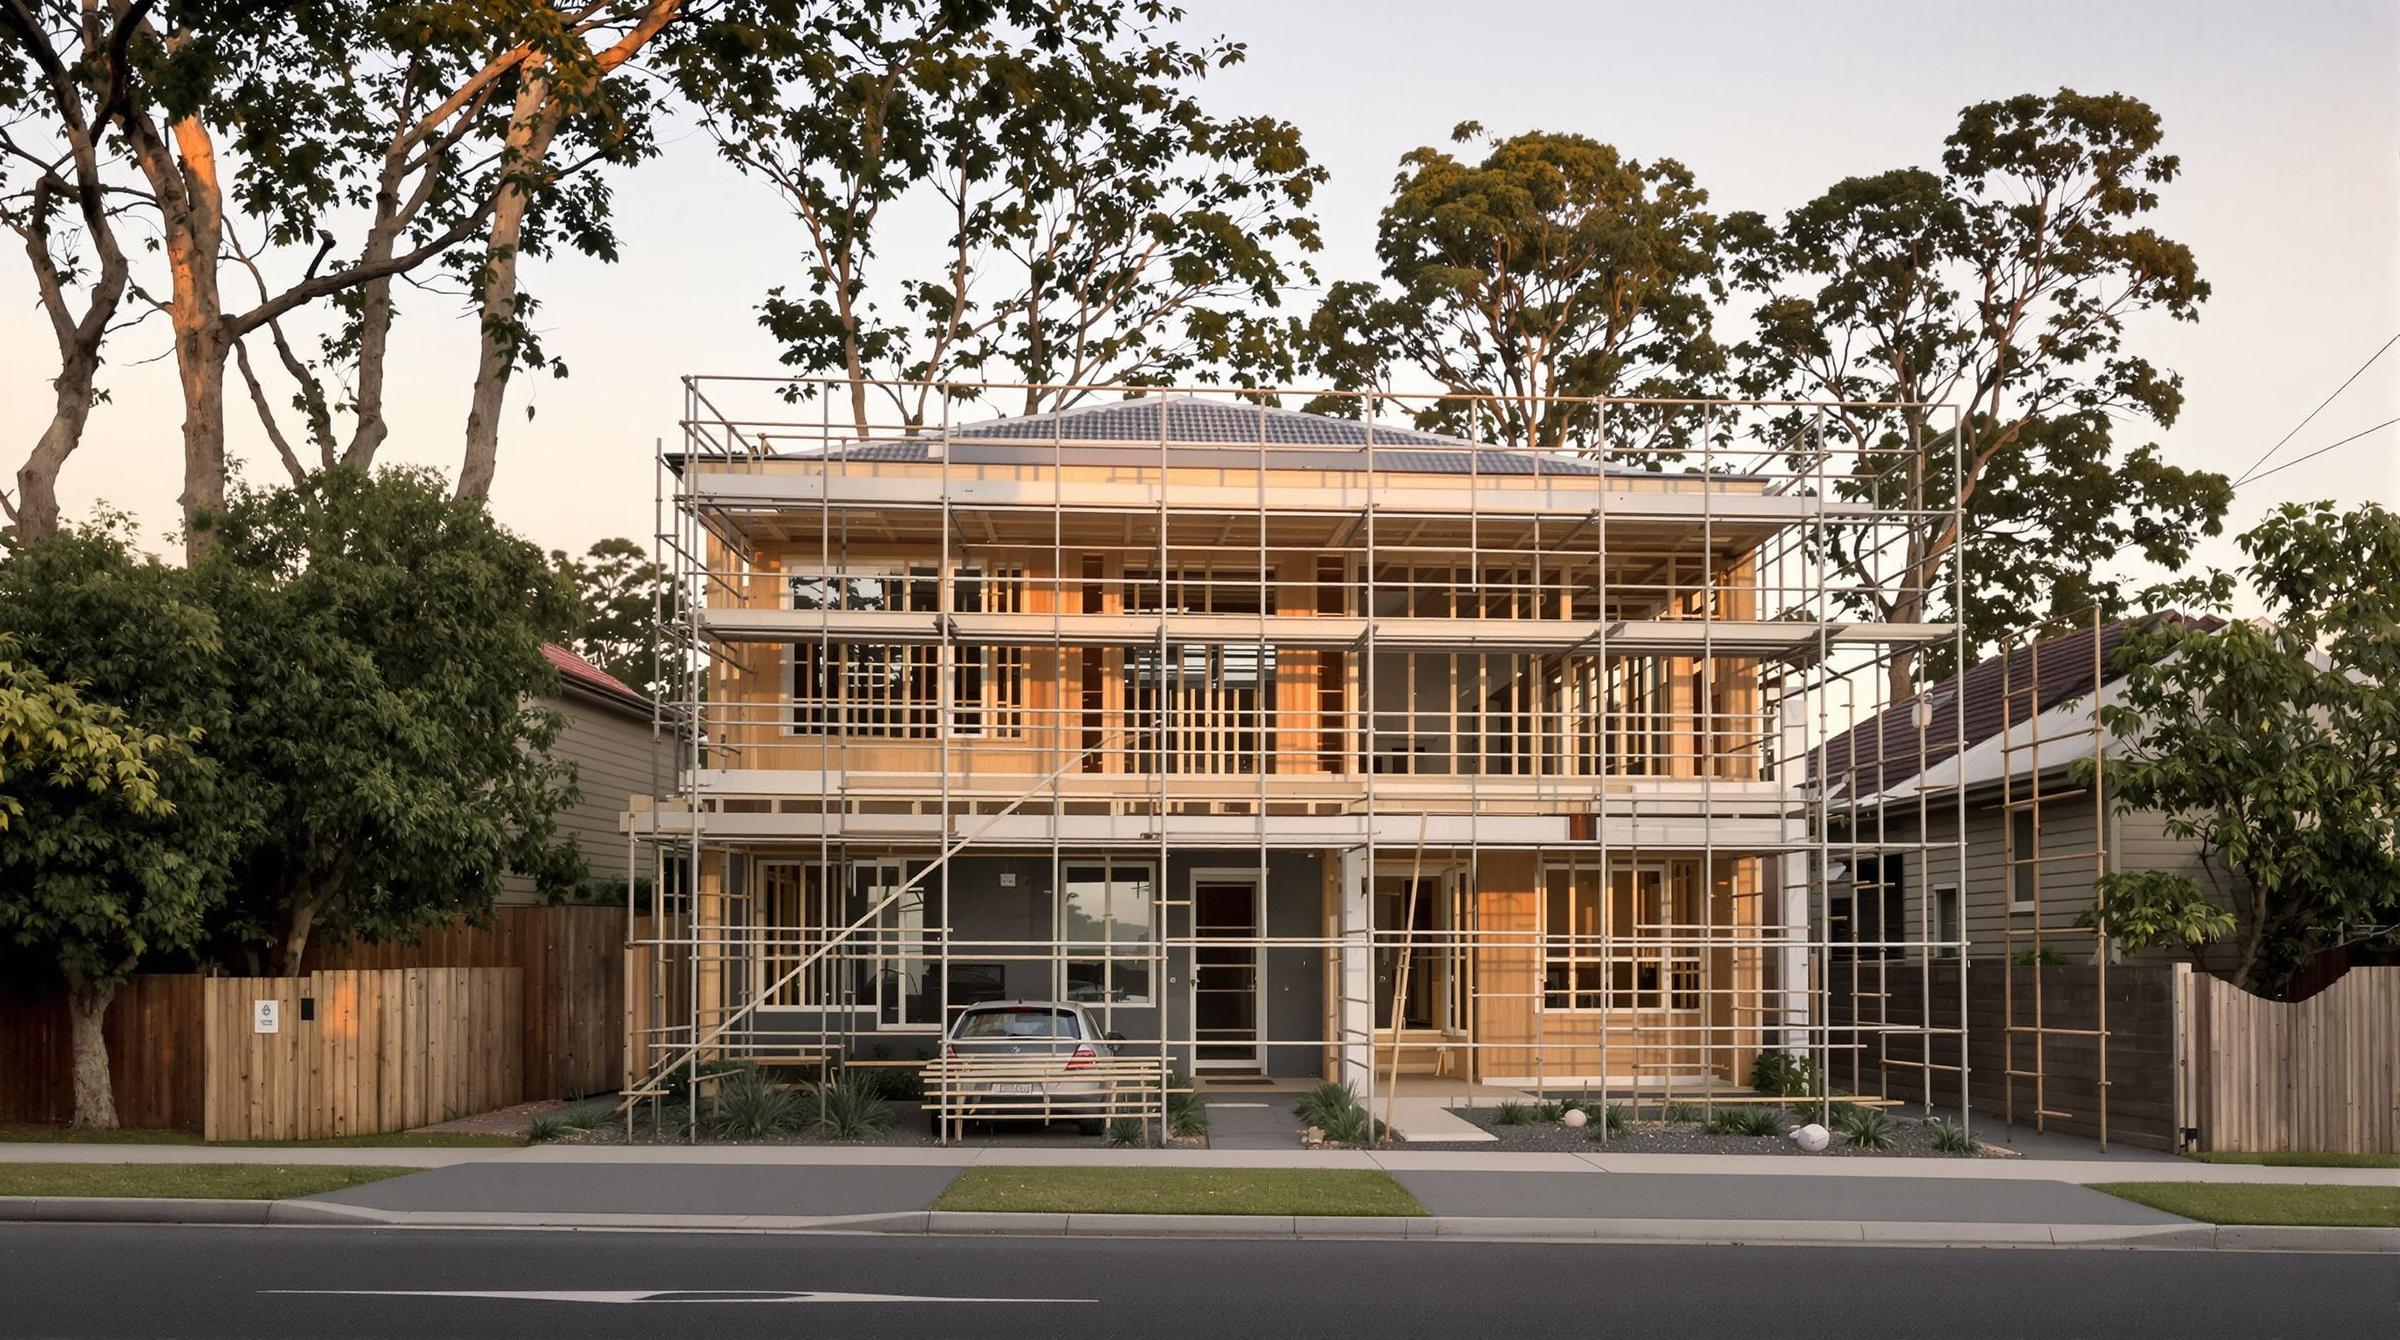
A construction loan releases funds in stages as the build progresses, rather than all at once. Typical stages include the deposit, slab or base, frame, lock-up, fixing and completion, with each progress claim from your builder paid after the lender confirms the work has been done. During construction you generally pay interest only on the amount drawn so far.
Your own contribution is usually used first. Most lenders require your deposit and other funds to be spent before they release loan funds. Once the build is complete, the loan typically converts to a standard home or investment loan, which is why we choose the end loan as carefully as the construction phase.
- Deposit and land settlement
- Base or slab stage
- Frame and lock-up
- Fixing and practical completion
What lenders need before they approve a build
Lenders assess both you and the project. They generally need a fixed-price building contract with a licensed builder, council-approved plans, specifications and evidence of home warranty insurance where required. The valuer assesses the land and the expected value on completion, which together determine how much the lender will lend.
Cost-plus contracts, owner-builder projects and contracts with large provisional sums are treated more cautiously, and some lenders will not accept them. Variations agreed after approval may need to be funded by you or reassessed by the lender. We review your contract early, so issues with the documentation are resolved before the application goes in.
- Fixed-price building contract
- Council-approved plans and specifications
- Builder's licence and insurance details
- Valuation on an as-if-complete basis
Talk it through with a director. A 20-minute strategy call, free and with no obligation.
Demolishing and rebuilding on your own land
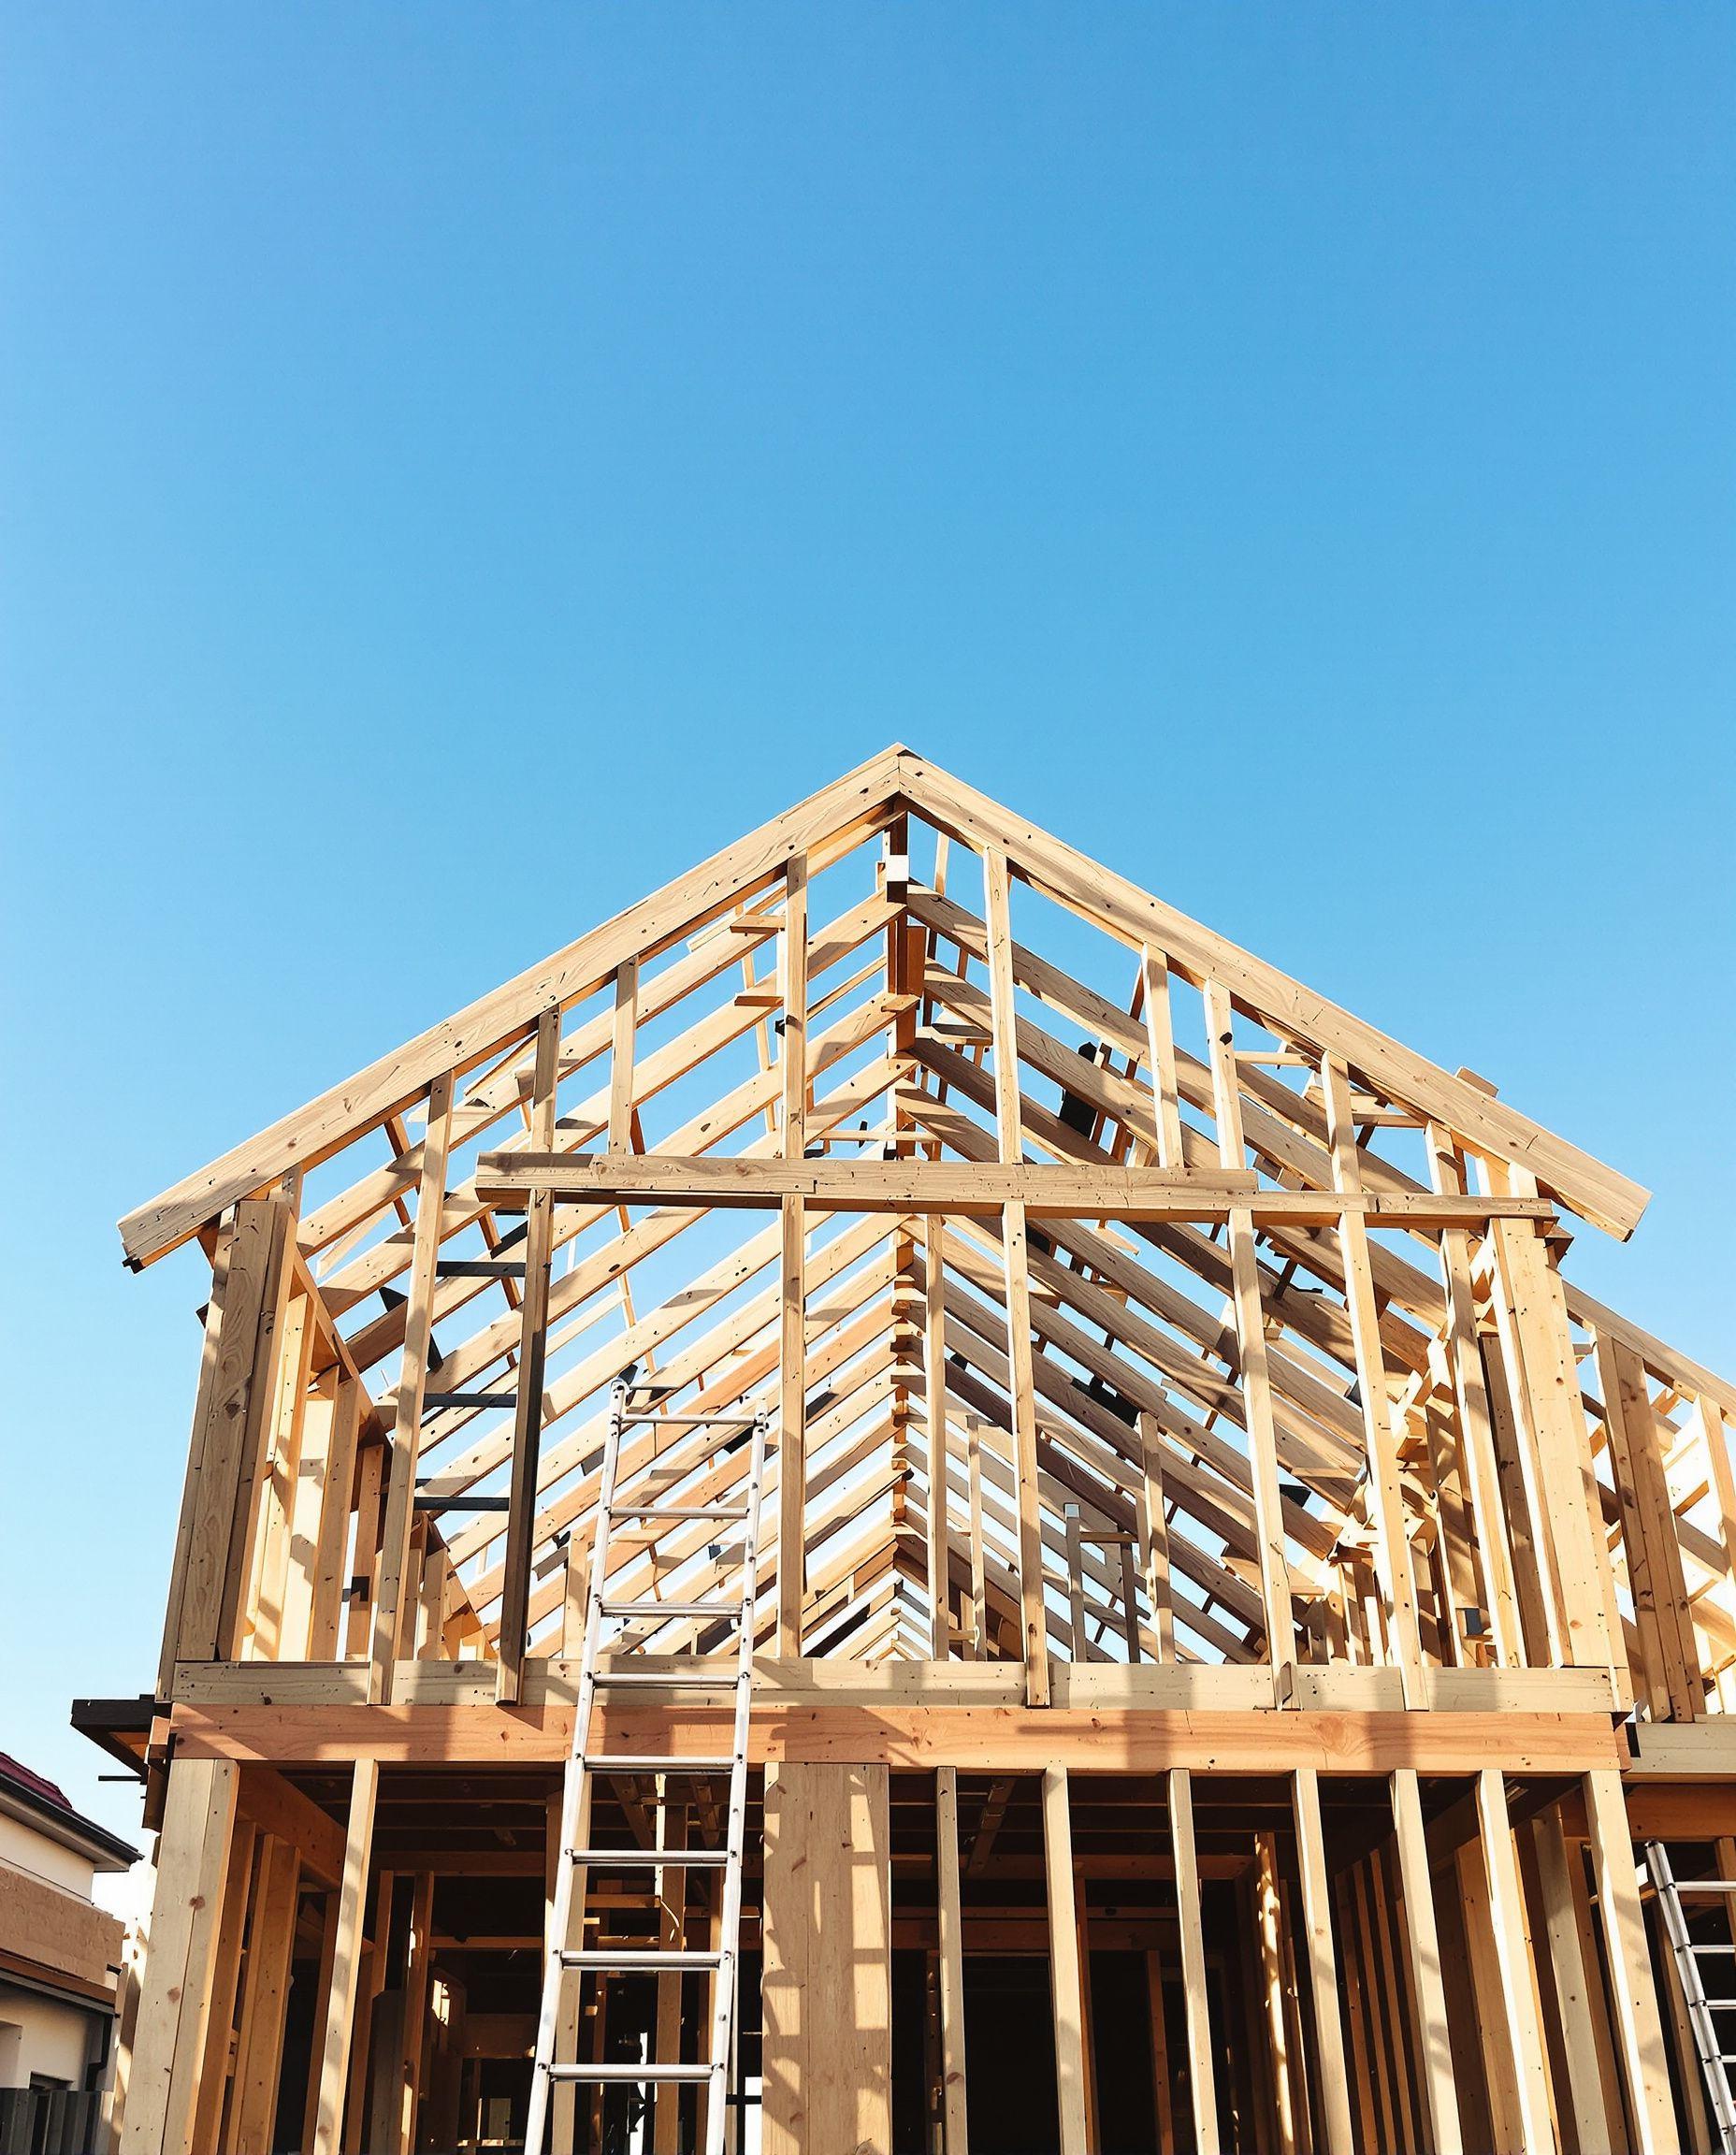
A knockdown-rebuild draws on equity in land you already own, which can reduce the cash needed upfront. The lender values the land once the existing house is removed and then the completed home, so the security position changes during the project.
There are practical points to plan for. You will need somewhere to live during the build, demolition and site costs often sit outside the builder's contract, and approvals can take longer than expected. Some lenders roll the existing loan and the new construction into one facility; others prefer separate splits. We structure the finance so the move from your current loan to the construction loan is clear.
- Demolition and site preparation costs
- Temporary accommodation during the build
- Council or private certifier approvals
- Existing loan restructured into the build
Costs and contingencies to plan for
Construction lending has costs that standard purchases do not. Lenders may charge progress payment or inspection fees at each stage. Interest accumulates as more funds are drawn, so repayments rise through the build, and you may be paying rent or another loan at the same time.
Builds rarely go exactly to plan. Weather, material costs and variations can change the final figure, and the lender will not usually increase the loan without a new assessment. We recommend keeping a contingency in savings or an offset account. Items outside the contract, such as landscaping, driveways, fencing and window coverings, also need funding, and some lenders will not lend for them.
Let’s take the next steps in your finance journey
One director from first call to settlement, and still here afterwards. A strategy call is free, takes 20 minutes and comes with no obligation.
Stage 1
Project review
We review your land, plans, builder and contract, and discuss your budget, contingency and plans for the property once complete.
Stage 2
Lender match
We choose a lender whose construction policy suits your contract type, builder and project, and confirm how progress payments will work.
Stage 3
Approval
We arrange the valuation, lodge the application with full building documentation and work through conditions with the credit team.
Stage 4
Progress draws
During the build we help you submit progress claims, liaise with the lender on inspections and keep payments moving to your builder.
Stage 5
Completion
At completion we confirm the loan converts correctly, review the end structure and check whether a rate or offset change is worthwhile.
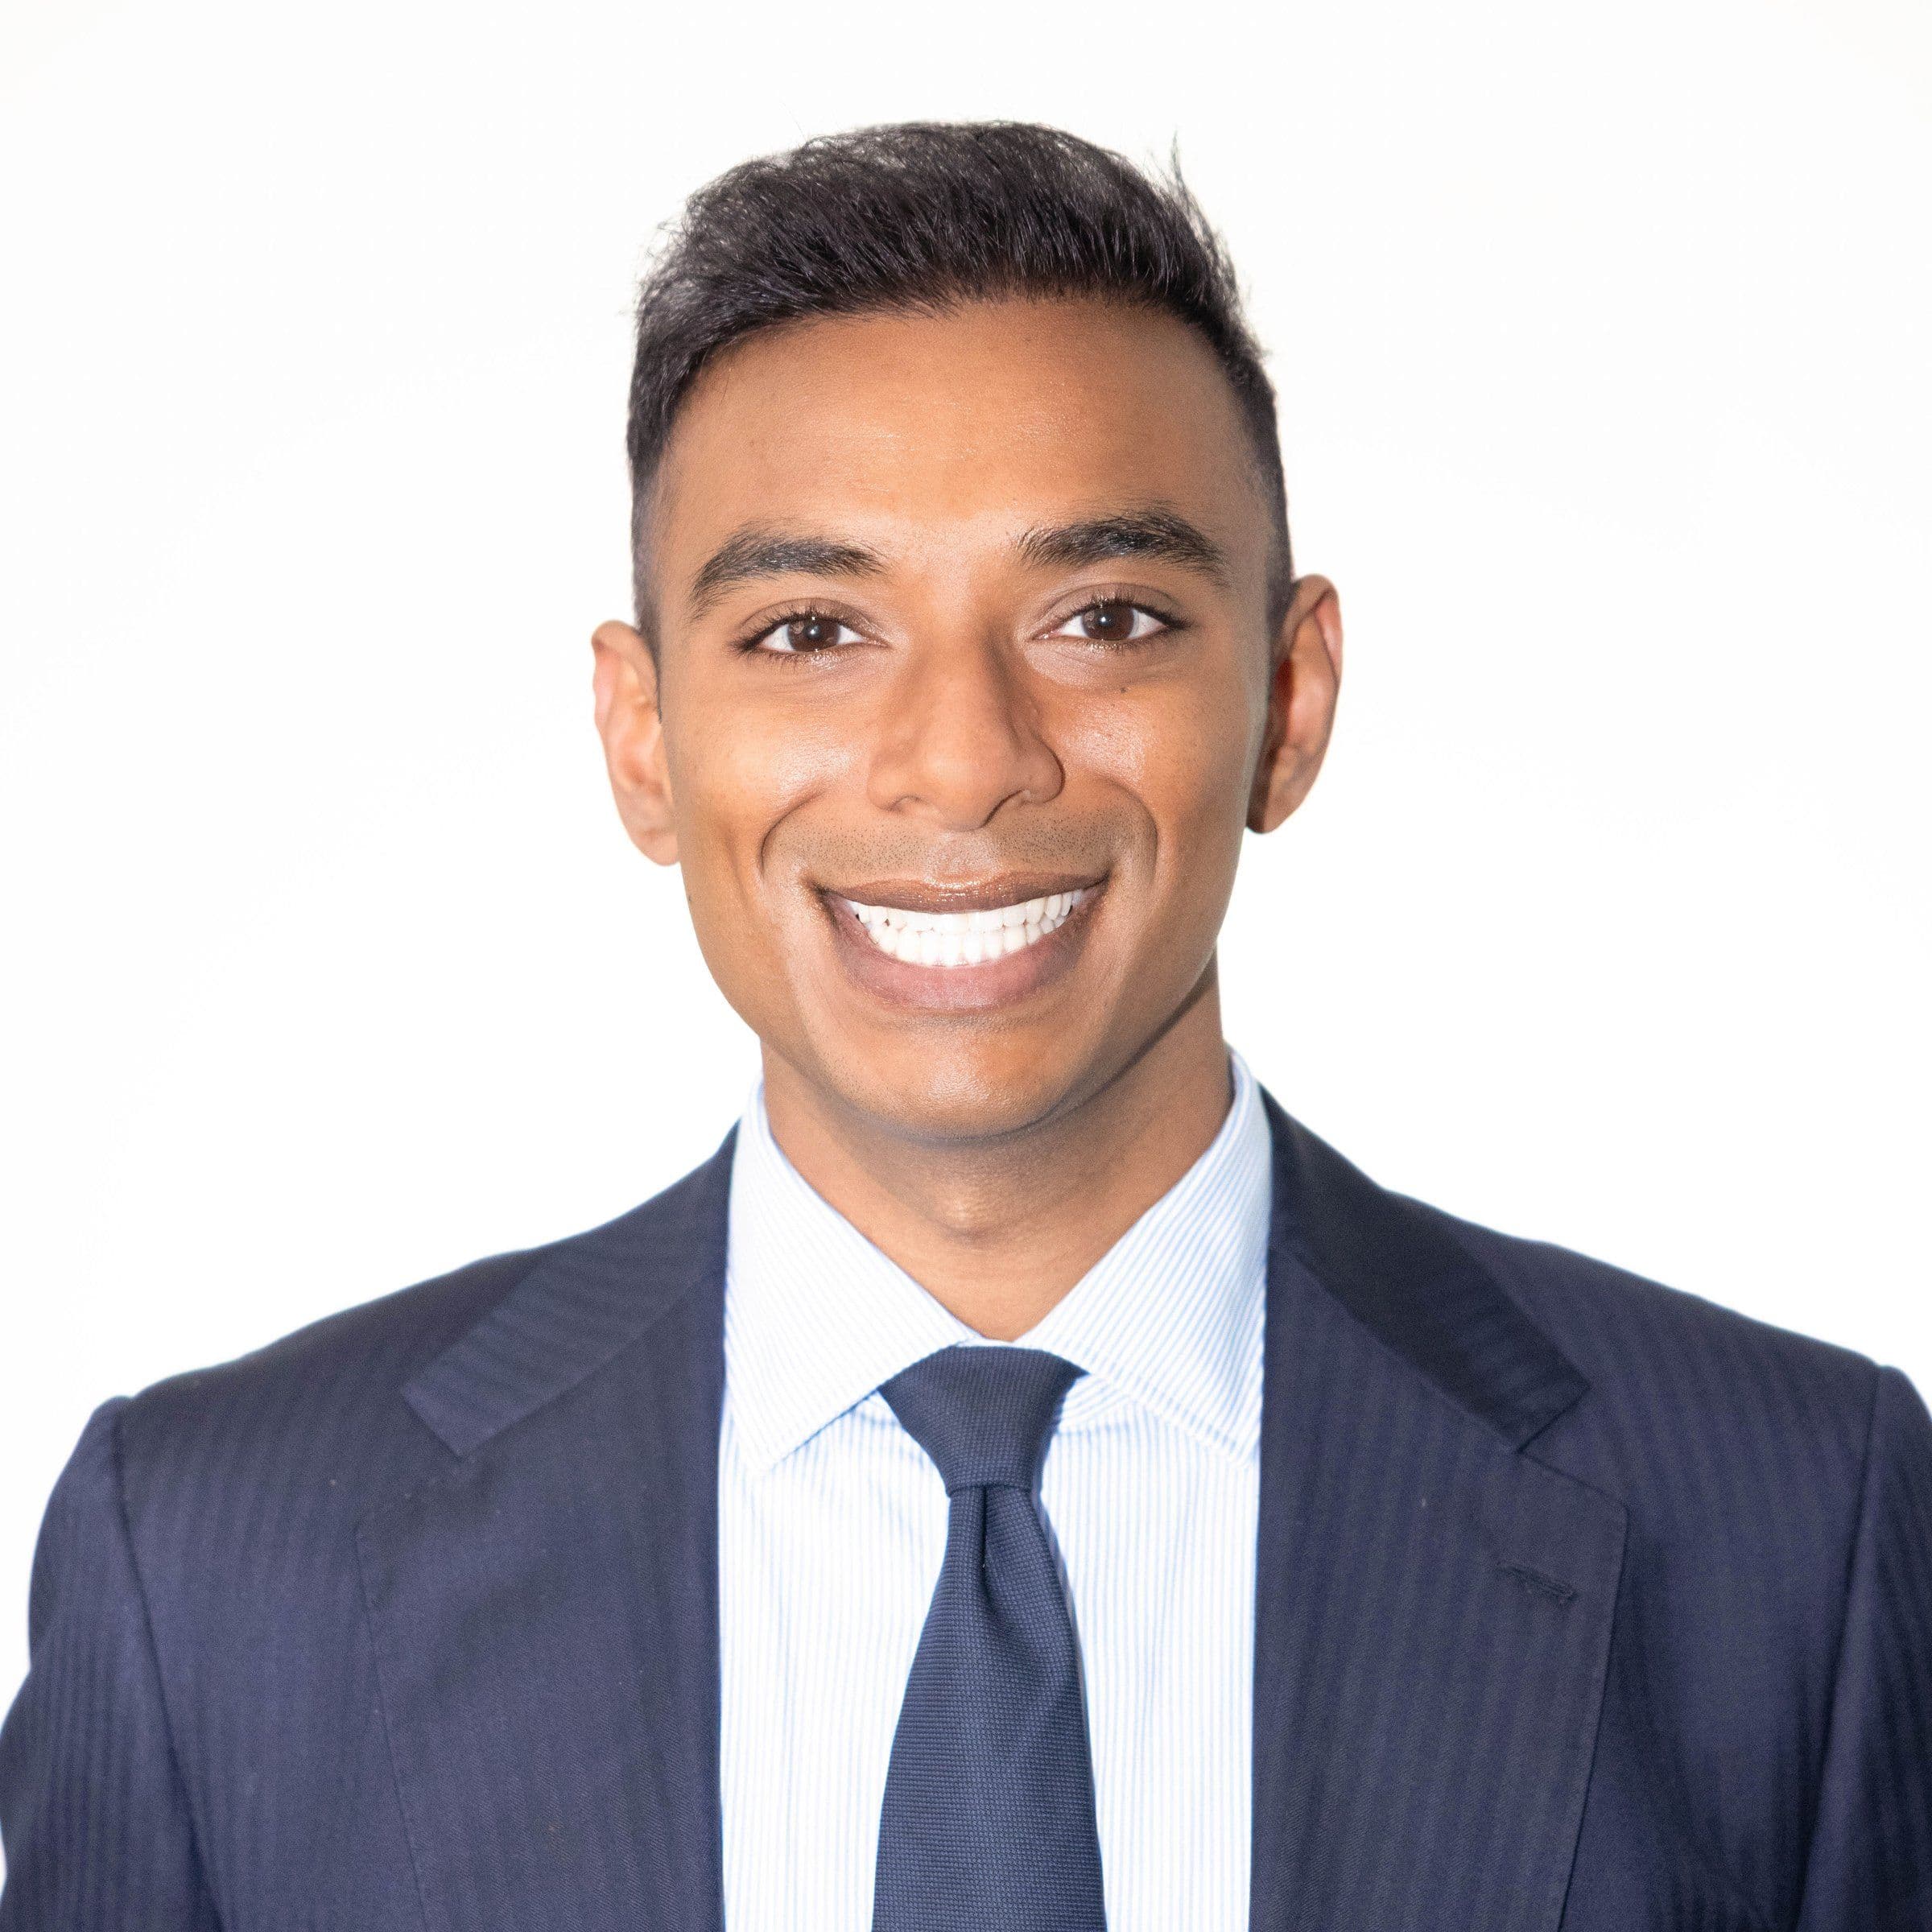
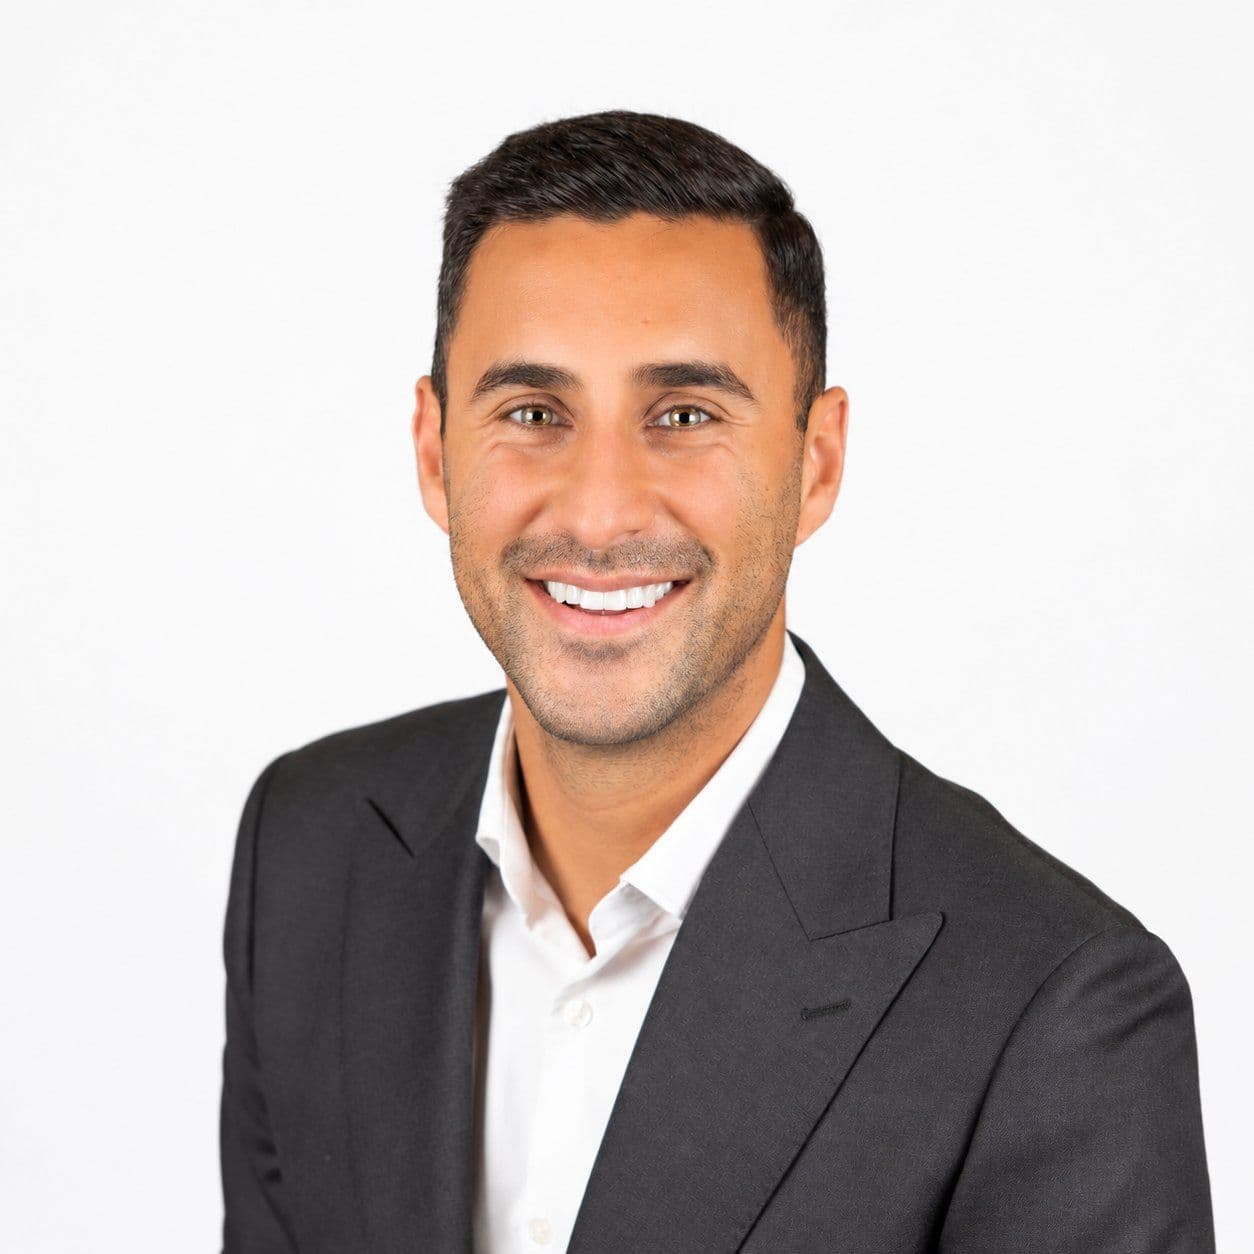
Speak with Tharun or Zain
Things to weigh up
Cost-plus contracts are harder
Many lenders prefer or require a fixed-price contract. Cost-plus or open-ended contracts may limit your lender options or require a larger contribution.
Variations may not be funded
Changes after approval often need your own funds or a fresh assessment. Finalise selections before the application is lodged where you can.
Your builder's standing matters
Lenders may review the builder's licence and standing. Check home warranty insurance and the builder's track record before you sign.
Valuations can fall short
If the on-completion valuation is below land plus contract price, you may need to contribute more. We test the contract against the valuation early.
Run the numbers
Weekly, fortnightly or monthly repayments, principal & interest or interest-only.
Monthly repayment
$3,935
- Total interest
- $766,517
- Total repaid
- $1,416,517
Estimate only. Not an offer or approval of credit. Every lender assesses differently.
Questions people ask before they build
Do I make full repayments while my home is being built?
Usually not. Most construction loans charge interest only on the amount drawn during the build, so repayments start lower and increase as each progress payment is made. When construction is complete, the loan normally moves to principal and interest repayments unless you arrange otherwise.
Can I do some of the work myself?
Lenders are cautious about owner-builder work and items outside a licensed builder's contract. Some will accept limited owner works with conditions, but many will not fund them. If you plan to do part of the work yourself, tell us early so we can find a lender whose policy fits.
Can I use a construction loan to build an investment property or duplex?
Many lenders offer construction finance for investment properties, including duplexes, assessed on your overall position and the expected rental income. Larger multi-dwelling projects may fall under development finance, which is assessed differently. We will tell you which category your project falls into and which lenders suit it.
What does a mortgage broker cost me?
In most cases, nothing. Lenders pay us a commission when your loan settles, and we disclose it in full in your Credit Proposal before you proceed. If a fee ever applies to your scenario, we tell you upfront, in writing.
You may also be considering
All services- Home LoansWe support clients through every stage of the purchase process, structuring lending solutions for owner-occupiers with a tailored, strategic approach.
- Investment LoansWe structure investment lending with the long game in mind – the right lender, the right structure and room to keep building.
- First Home BuyersWe guide first home buyers through the entire home buying journey, from understanding borrowing capacity to accessing what government schemes they may be eligible for. We work with you during this pivotal period in your life to make your entry into the property market as clear and achievable as possible.
Let’s map out your next move
Tell us where you are and where you want to be. A director will come back to you within one business day.
- Tharun Rameshbabu
- 0493 125 004tharun@terrainfp.com
- Zain Sumar
- 0494 503 777zain@terrainfp.com
- Office
- Level 3, 55 Pyrmont Bridge Road, Pyrmont NSW 2009