Buy a home
Buying the home you’ll live in, structured properly from day one.
We help owner-occupiers choose the right lender and the right loan structure, so your home loan suits how you live, earn and plan to repay, for the life of the loan.
Client reviews
- “made the whole process easy”Lahari K · Google ·
- “incredibly easy and stress-free”Laura Rossi · Google ·
- “incredibly responsive, hardworking”Martin V · Google ·
- “cannot speak highly enough of the team”Jake Frei · Google ·
- “working with Tharun for years”Vidhu Shekhar · Google ·
- “supported and genuinely cared for”Andrea Veltom · Google ·
- “seamless from start to finish”John Z · Google ·
- “made the whole process incredibly easy”Kevin Fernandopulle · Google ·
- “a much better interest rate”Bradley L · Google ·
- “Great communication, great outcome”Charles-emile · Google ·
- “Best in the business!”Saba Khan · Google ·
- “an amazing advisor, fast, efficient”harold quek · Google ·
- “seamless and stress free”Victor Zhou · Google ·
- “incredibly professional and responsive”steven wu · Google ·
- “went above and beyond”Jennifer Kim · Google ·
- “I genuinely cannot recommend him enough”David Maxwell · Google ·
- “I wouldn’t have done this without him”Phaedra McGhie · Google ·
Our approach
We help you secure a home loan that is competitive on price and structured around how you live, so it keeps working for you long after settlement.
Who this suits
- 1. Upgraders buying their next home
- 2. Downsizers moving to something smaller
- 3. Families relocating within Sydney
- 4. Self-employed buyers with complex income
- 5. Professionals with bonus or commission income
- 6. Buyers selling and buying at once
Talk it through with a director. A 20-minute strategy call, free and with no obligation.
Leveraging over 50 lending partners to achieve these results for you
From the major banks to specialist lenders, we compare policy and pricing to find the loan that fits.
- Bank of Queensland
- Capital Finance
- HSBC
- Medfin
- NWC Finance
- Paramount Residential
- Suncorp
What an owner-occupier home loan covers
An owner-occupier home loan is secured against the property you live in. Lenders generally treat it as their lowest-risk lending, which is why pricing and policy for owner-occupiers often differ from investment loans. The loan you choose shapes far more than your repayment – it affects how easily you can pay it down, move house or later turn the property into an investment.
At TFP we start with how you actually manage money. Do you hold savings you want close at hand? Is your income regular or variable? Are you likely to move in the medium term? Those answers point us to the features, lenders and structure worth considering, before we compare pricing across more than 50 lenders.
- Principal and interest repayments as standard
- Offset or redraw to manage savings
- Fixed, variable or split rate options
- Loan portability with some lenders
How lenders assess your application
Lenders look at three things: your capacity to repay, the security and your conduct. Capacity is assessed on income, existing debts, living expenses and dependants, then tested against a buffer above the actual rate, so the amount you can borrow is usually less than the repayments alone suggest. Credit card limits count against you even when the balance is nil.
The property must meet the lender's security criteria, and the valuation can differ from the contract price. Your credit file and bank statements show how you handle money. As former CBA lenders, Tharun and Zain know how credit teams read an application, and we present yours so the key facts are clear from the first page.
- Income, including overtime, bonuses and allowances
- Declared and benchmarked living expenses
- Existing debts and credit card limits
- Property type, location and valuation
Talk it through with a director. A 20-minute strategy call, free and with no obligation.
Offset, splits and fixed or variable rates
Structure is where a home loan earns its keep. An offset account linked to a variable loan reduces the balance on which interest is charged while keeping your savings accessible. Redraw does something similar but can carry restrictions on access. Fixing some or all of the loan gives repayment certainty for the fixed term, though it usually limits extra repayments and can trigger break costs if you exit early.
Many clients use a split: part fixed for certainty, part variable with an offset for flexibility. If there is a chance the home becomes an investment later, we think about that now, because how the loan is set up can matter for future deductibility. Your accountant should confirm the tax side.
The upfront and ongoing costs to plan for
Beyond the deposit, buyers should budget for stamp duty, legal and conveyancing fees, building and pest inspections, and lender fees such as application, valuation or settlement charges. If your deposit is smaller than a lender's standard threshold, lenders mortgage insurance may apply. It is often added to the loan, which increases the amount you repay over time.
On an ongoing basis, some loans charge an annual package fee in exchange for features like offset accounts and pricing discounts. Whether that is worthwhile depends on how you will use the features. We set out the full cost picture for each option we recommend, so you compare the real cost of each loan rather than the headline rate.
- Stamp duty and government registration fees
- Conveyancing and inspection costs
- Lenders mortgage insurance, where applicable
- Package or account-keeping fees
Let’s take the next steps in your finance journey
One director from first call to settlement, and still here afterwards. A strategy call is free, takes 20 minutes and comes with no obligation.
Stage 1
Discovery call
We talk through the property you're looking for, your income, savings and plans, and what matters most to you in a loan.
Stage 2
Lender comparison
We compare policy and pricing across our lender panel and explain why we recommend a particular lender and structure.
Stage 3
Application
We prepare and lodge a complete application, deal directly with the credit assessor and keep you informed at each stage.
Stage 4
Settlement
We coordinate with your conveyancer and the lender so funds are ready and settlement proceeds as scheduled.
Stage 5
Ongoing review
After settlement we check in periodically to make sure your rate and structure still suit you as your circumstances change.
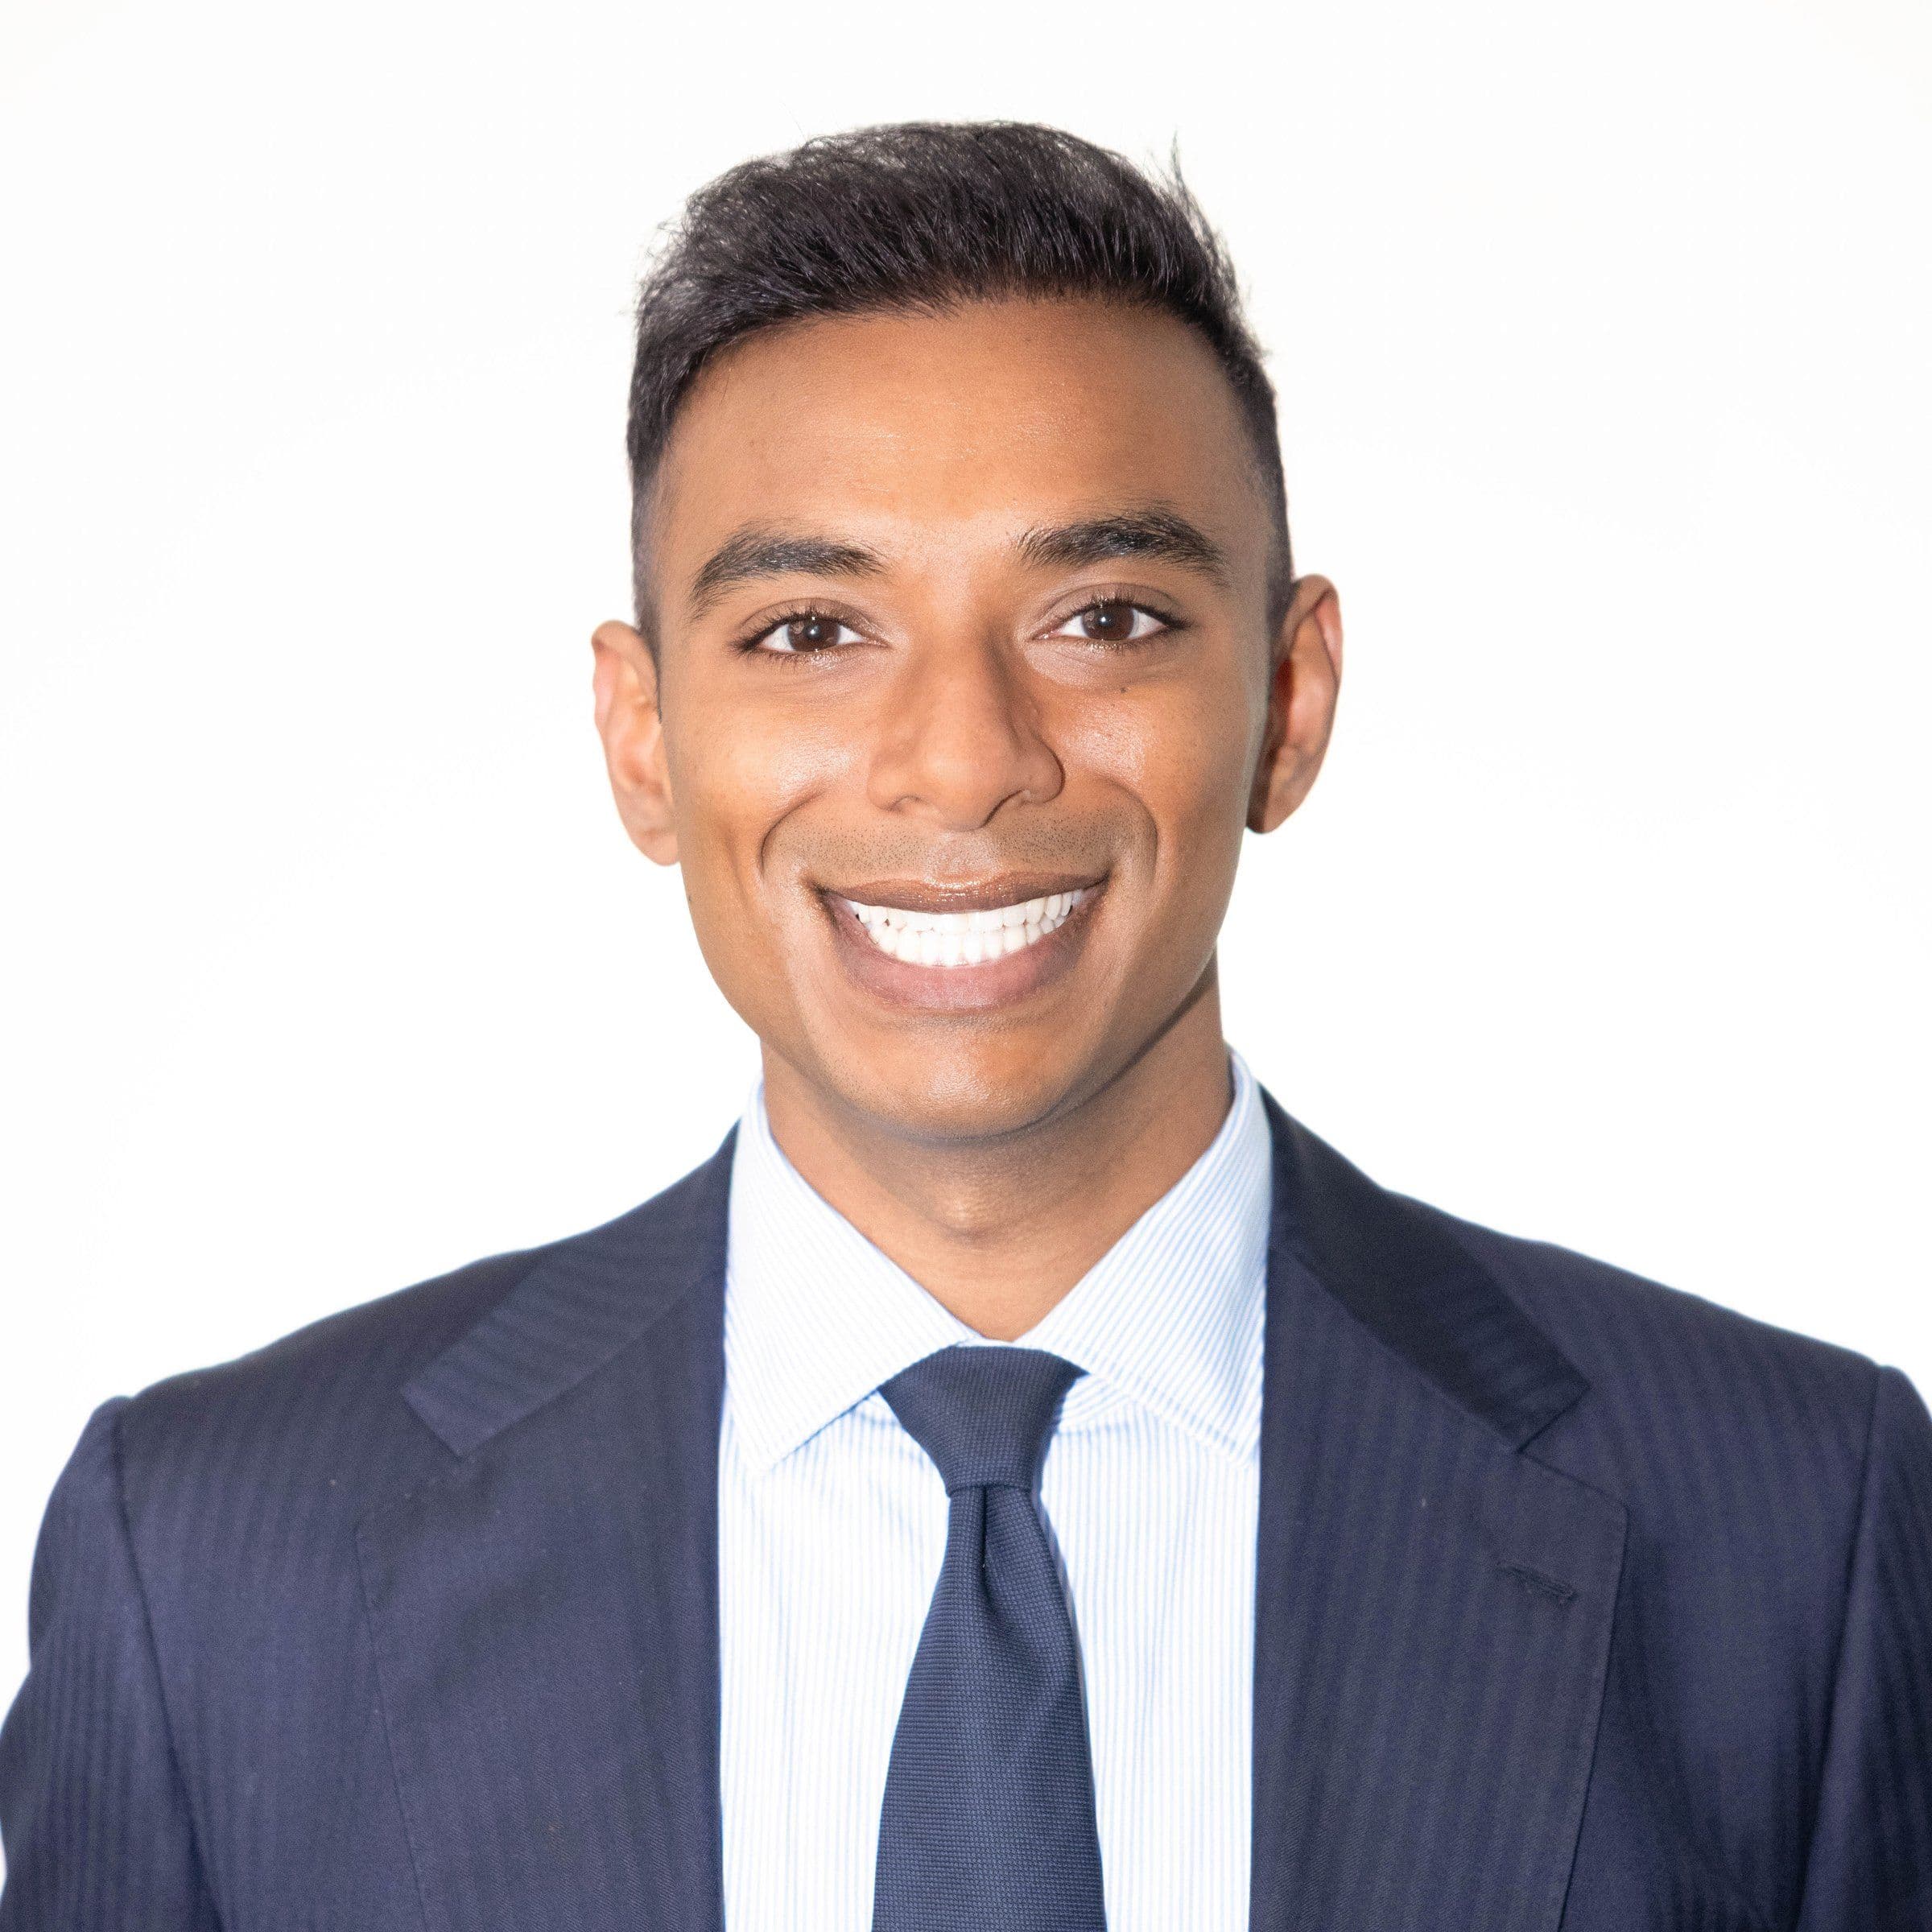
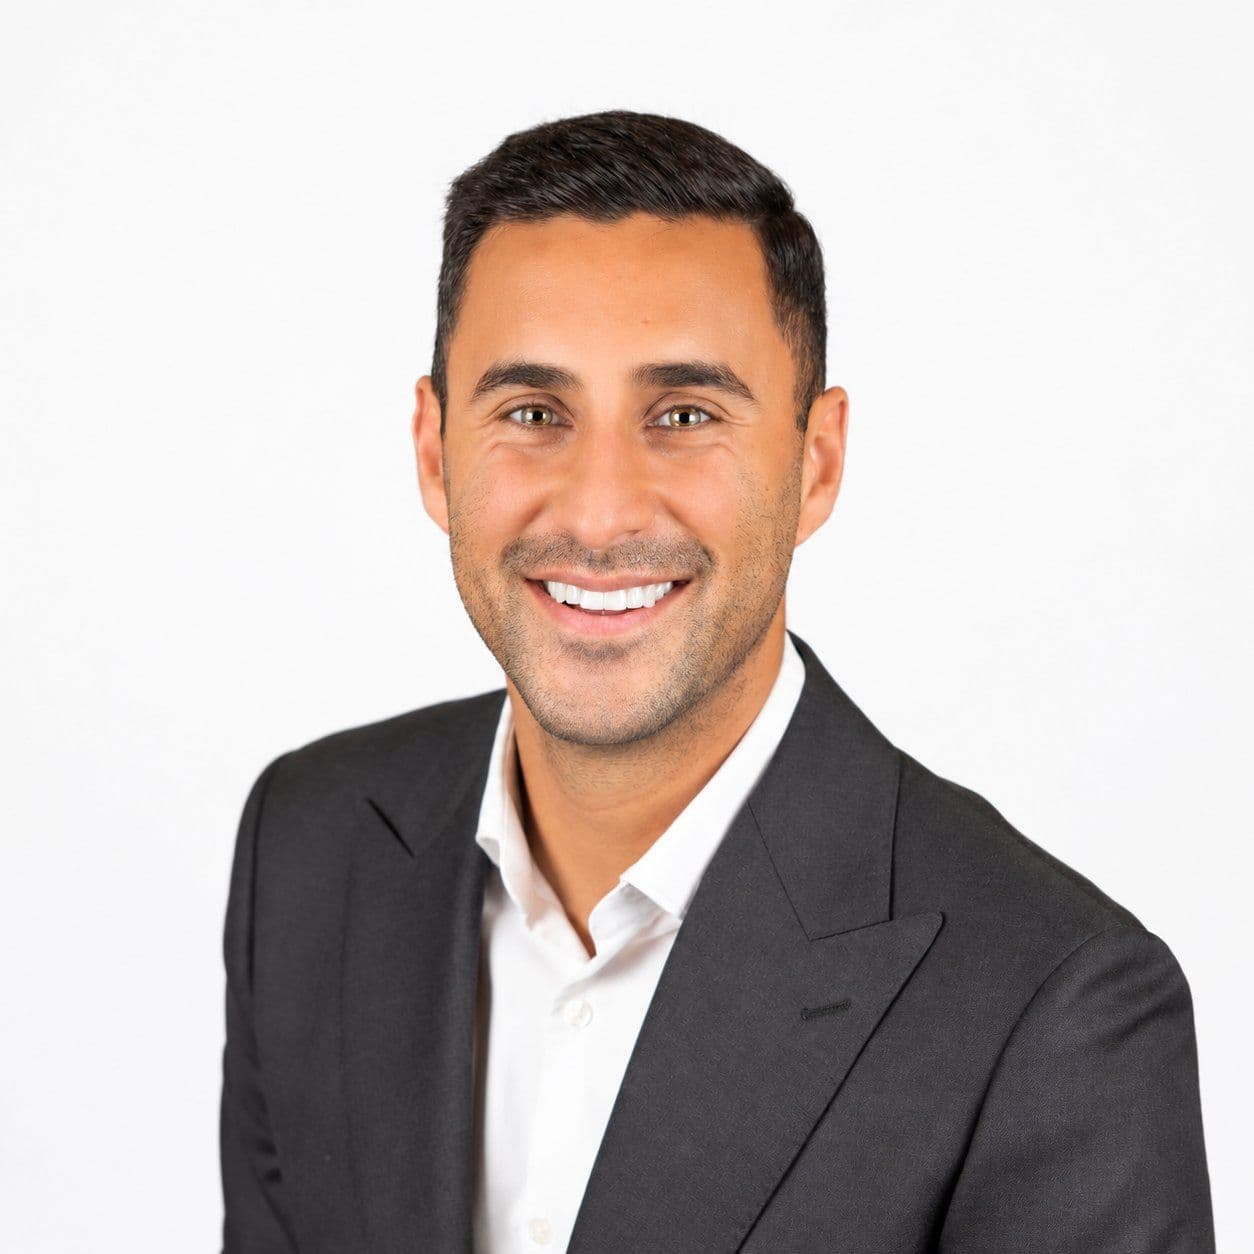
Speak with Tharun or Zain
Things to weigh up
Valuations can come in short
If the lender values the property below the purchase price, the difference usually has to come from your own funds. Some lenders allow a valuation before you commit.
Unused credit limits reduce borrowing
Lenders assess credit cards on the limit, not the balance. Reducing or closing cards you don't need before applying can improve your position.
Fixed rates carry break costs
Exiting or refinancing a fixed loan early may incur break costs. Consider your plans before fixing the whole balance.
Buying before selling needs a plan
If you buy before you sell, you may need bridging finance or a clear sale strategy. Lenders assess this carefully, so we plan it before you sign.
Run the numbers
Estimate how much you could borrow, with the serviceability buffer lenders apply.
You could borrow around
$1,349,000
Assessed at 9.09% (rate + 3% buffer)
- Estimated repayment
- $8,166/mth
- Living expenses used
- $3,500/mth
Estimate only. Not an offer or approval of credit. Every lender assesses differently.
Questions home buyers typically ask
Should I choose an offset account or redraw?
Both reduce the interest you pay by lowering the balance it is calculated on. An offset is a separate transaction account, so your savings stay distinct from the loan, which many clients prefer if the home may become an investment later. Redraw can be simpler, but access rules vary by lender. We explain how each lender handles both.
Can I buy my next home before I sell my current one?
It can be possible. Options include bridging finance, which some lenders offer while you sell, or borrowing against equity in your current home for the deposit. Each approach carries different costs and risks, so we model the scenarios with you before you commit to a purchase.
How is bonus, overtime or commission income treated?
Lenders differ considerably. Some use only a portion of variable income, some require a longer history of receiving it, and some accept it more readily for certain occupations. Knowing which lenders favour your income type is one of the main ways we add value.
What does a mortgage broker cost me?
In most cases, nothing. Lenders pay us a commission when your loan settles, and we disclose it in full in your Credit Proposal before you proceed. If a fee ever applies to your scenario, we tell you upfront, in writing.
You may also be considering
All services- Pre-ApprovalKnow your number before you bid. We secure pre-approval with the lender best suited to your purchase, so you can act with confidence.
- RefinancingWe review and restructure existing lending to secure more competitive rates, unlock equity, or consolidate debt – ensuring your finance continues to work in your favour.
- First Home BuyersWe guide first home buyers through the entire home buying journey, from understanding borrowing capacity to accessing what government schemes they may be eligible for. We work with you during this pivotal period in your life to make your entry into the property market as clear and achievable as possible.
Let’s map out your next move
Tell us where you are and where you want to be. A director will come back to you within one business day.
- Tharun Rameshbabu
- 0493 125 004tharun@terrainfp.com
- Zain Sumar
- 0494 503 777zain@terrainfp.com
- Office
- Level 3, 55 Pyrmont Bridge Road, Pyrmont NSW 2009