Buy a home
Your first property, made clear and achievable.
Buying your first home means new terms, new costs and many decisions at once. We explain each step in plain English and find a lender whose policy fits your situation.
Client reviews
- “made the whole process easy”Lahari K · Google ·
- “incredibly easy and stress-free”Laura Rossi · Google ·
- “incredibly responsive, hardworking”Martin V · Google ·
- “cannot speak highly enough of the team”Jake Frei · Google ·
- “working with Tharun for years”Vidhu Shekhar · Google ·
- “supported and genuinely cared for”Andrea Veltom · Google ·
- “seamless from start to finish”John Z · Google ·
- “made the whole process incredibly easy”Kevin Fernandopulle · Google ·
- “a much better interest rate”Bradley L · Google ·
- “Great communication, great outcome”Charles-emile · Google ·
- “Best in the business!”Saba Khan · Google ·
- “an amazing advisor, fast, efficient”harold quek · Google ·
- “seamless and stress free”Victor Zhou · Google ·
- “incredibly professional and responsive”steven wu · Google ·
- “went above and beyond”Jennifer Kim · Google ·
- “I genuinely cannot recommend him enough”David Maxwell · Google ·
- “I wouldn’t have done this without him”Phaedra McGhie · Google ·
Our approach
We guide you from first budget to settlement, making sense of schemes, deposits and lenders, so you can buy your first home with confidence.
Who this suits
- 1. First-time buyers in Sydney and NSW
- 2. Couples combining savings for the first time
- 3. Buyers with a smaller deposit
- 4. Singles buying on one income
- 5. Buyers with family support or a guarantor
- 6. Early-career professionals and recent graduates
Talk it through with a director. A 20-minute strategy call, free and with no obligation.
Leveraging over 50 lending partners to achieve these results for you
From the major banks to specialist lenders, we compare policy and pricing to find the loan that fits.
- Bank of Queensland
- Capital Finance
- HSBC
- Medfin
- NWC Finance
- Paramount Residential
- Suncorp
What you need before you start looking
The first step is understanding what you can realistically borrow and what you will need in savings. Your borrowing capacity depends on your income, debts, living expenses and the lender's assessment rate. Your savings need to cover more than the deposit – stamp duty, legal fees, inspections and moving costs all come out of the same pool.
Lenders also want to see genuine savings, meaning money you have built up yourself over time, though policies vary. Gifts from family are often accepted with the right documentation. We review your bank statements, payslips and credit file early, so any issues are found before you fall for a property rather than after.
- Recent payslips and employment details
- Bank statements showing your savings history
- Photo identification
- Details of debts, including HECS-HELP
First home buyer schemes and concessions
Federal and NSW first home buyer schemes and concessions may reduce the stamp duty you pay or allow you to buy with a smaller deposit without paying lenders mortgage insurance. Each scheme has its own eligibility rules, which can include income caps, property price caps, residency requirements and lists of participating lenders. These rules change, sometimes with little notice.
We confirm the current criteria at the time you apply and check whether you are likely to qualify. Where you may be eligible for more than one scheme, we explain how they interact and which lenders participate. Schemes can be valuable, but they are not always the best fit, so we compare the result against standard lending options too.
Talk it through with a director. A 20-minute strategy call, free and with no obligation.
Smaller deposits, LMI and family guarantees
Some lenders accept a smaller deposit with lenders mortgage insurance. LMI protects the lender, not you, and its cost can be significant, but it may let you buy sooner rather than keep saving while prices move. Some lenders waive LMI for borrowers in particular professions.
A family guarantee is another route. A parent or close relative offers equity in their own property as additional security, which may reduce or remove the need for LMI. It is a serious commitment for the guarantor, and we recommend they obtain independent legal advice. We also explain how the guarantee can later be released as your loan reduces or your property's value changes.
- Lenders mortgage insurance with a smaller deposit
- Government-backed low-deposit schemes, where eligible
- Family guarantee using a relative's equity
- Gifted funds with appropriate documentation
Picking features you'll actually use
First home buyers are often shown long lists of features. The ones that matter most are usually simple: a competitive variable rate, an offset account if you will keep savings on hand, and the ability to make extra repayments without penalty. A package loan can make sense if its discounts outweigh the annual fee.
We also think ahead. If you might rent the property out later or upgrade down the track, the structure you set up now can make that move easier. Our role is to explain the trade-offs plainly, compare across more than 50 lenders and recommend a loan you fully understand before you sign.
Let’s take the next steps in your finance journey
One director from first call to settlement, and still here afterwards. A strategy call is free, takes 20 minutes and comes with no obligation.
Stage 1
First conversation
We learn about your income, savings, goals and the kind of property you're considering, and answer the questions you've been unsure about.
Stage 2
Readiness check
We review your documents and credit file, estimate borrowing capacity and confirm the schemes and concessions you may be eligible for.
Stage 3
Pre-approval
We obtain pre-approval with a suitable lender so you can search and make offers with a clear budget.
Stage 4
Purchase to settlement
Once you find a property, we move to formal approval, liaise with your conveyancer and keep every party aligned through to settlement.
Stage 5
After settlement
We stay in touch, review your loan as your circumstances change and help when you're ready for your next step.
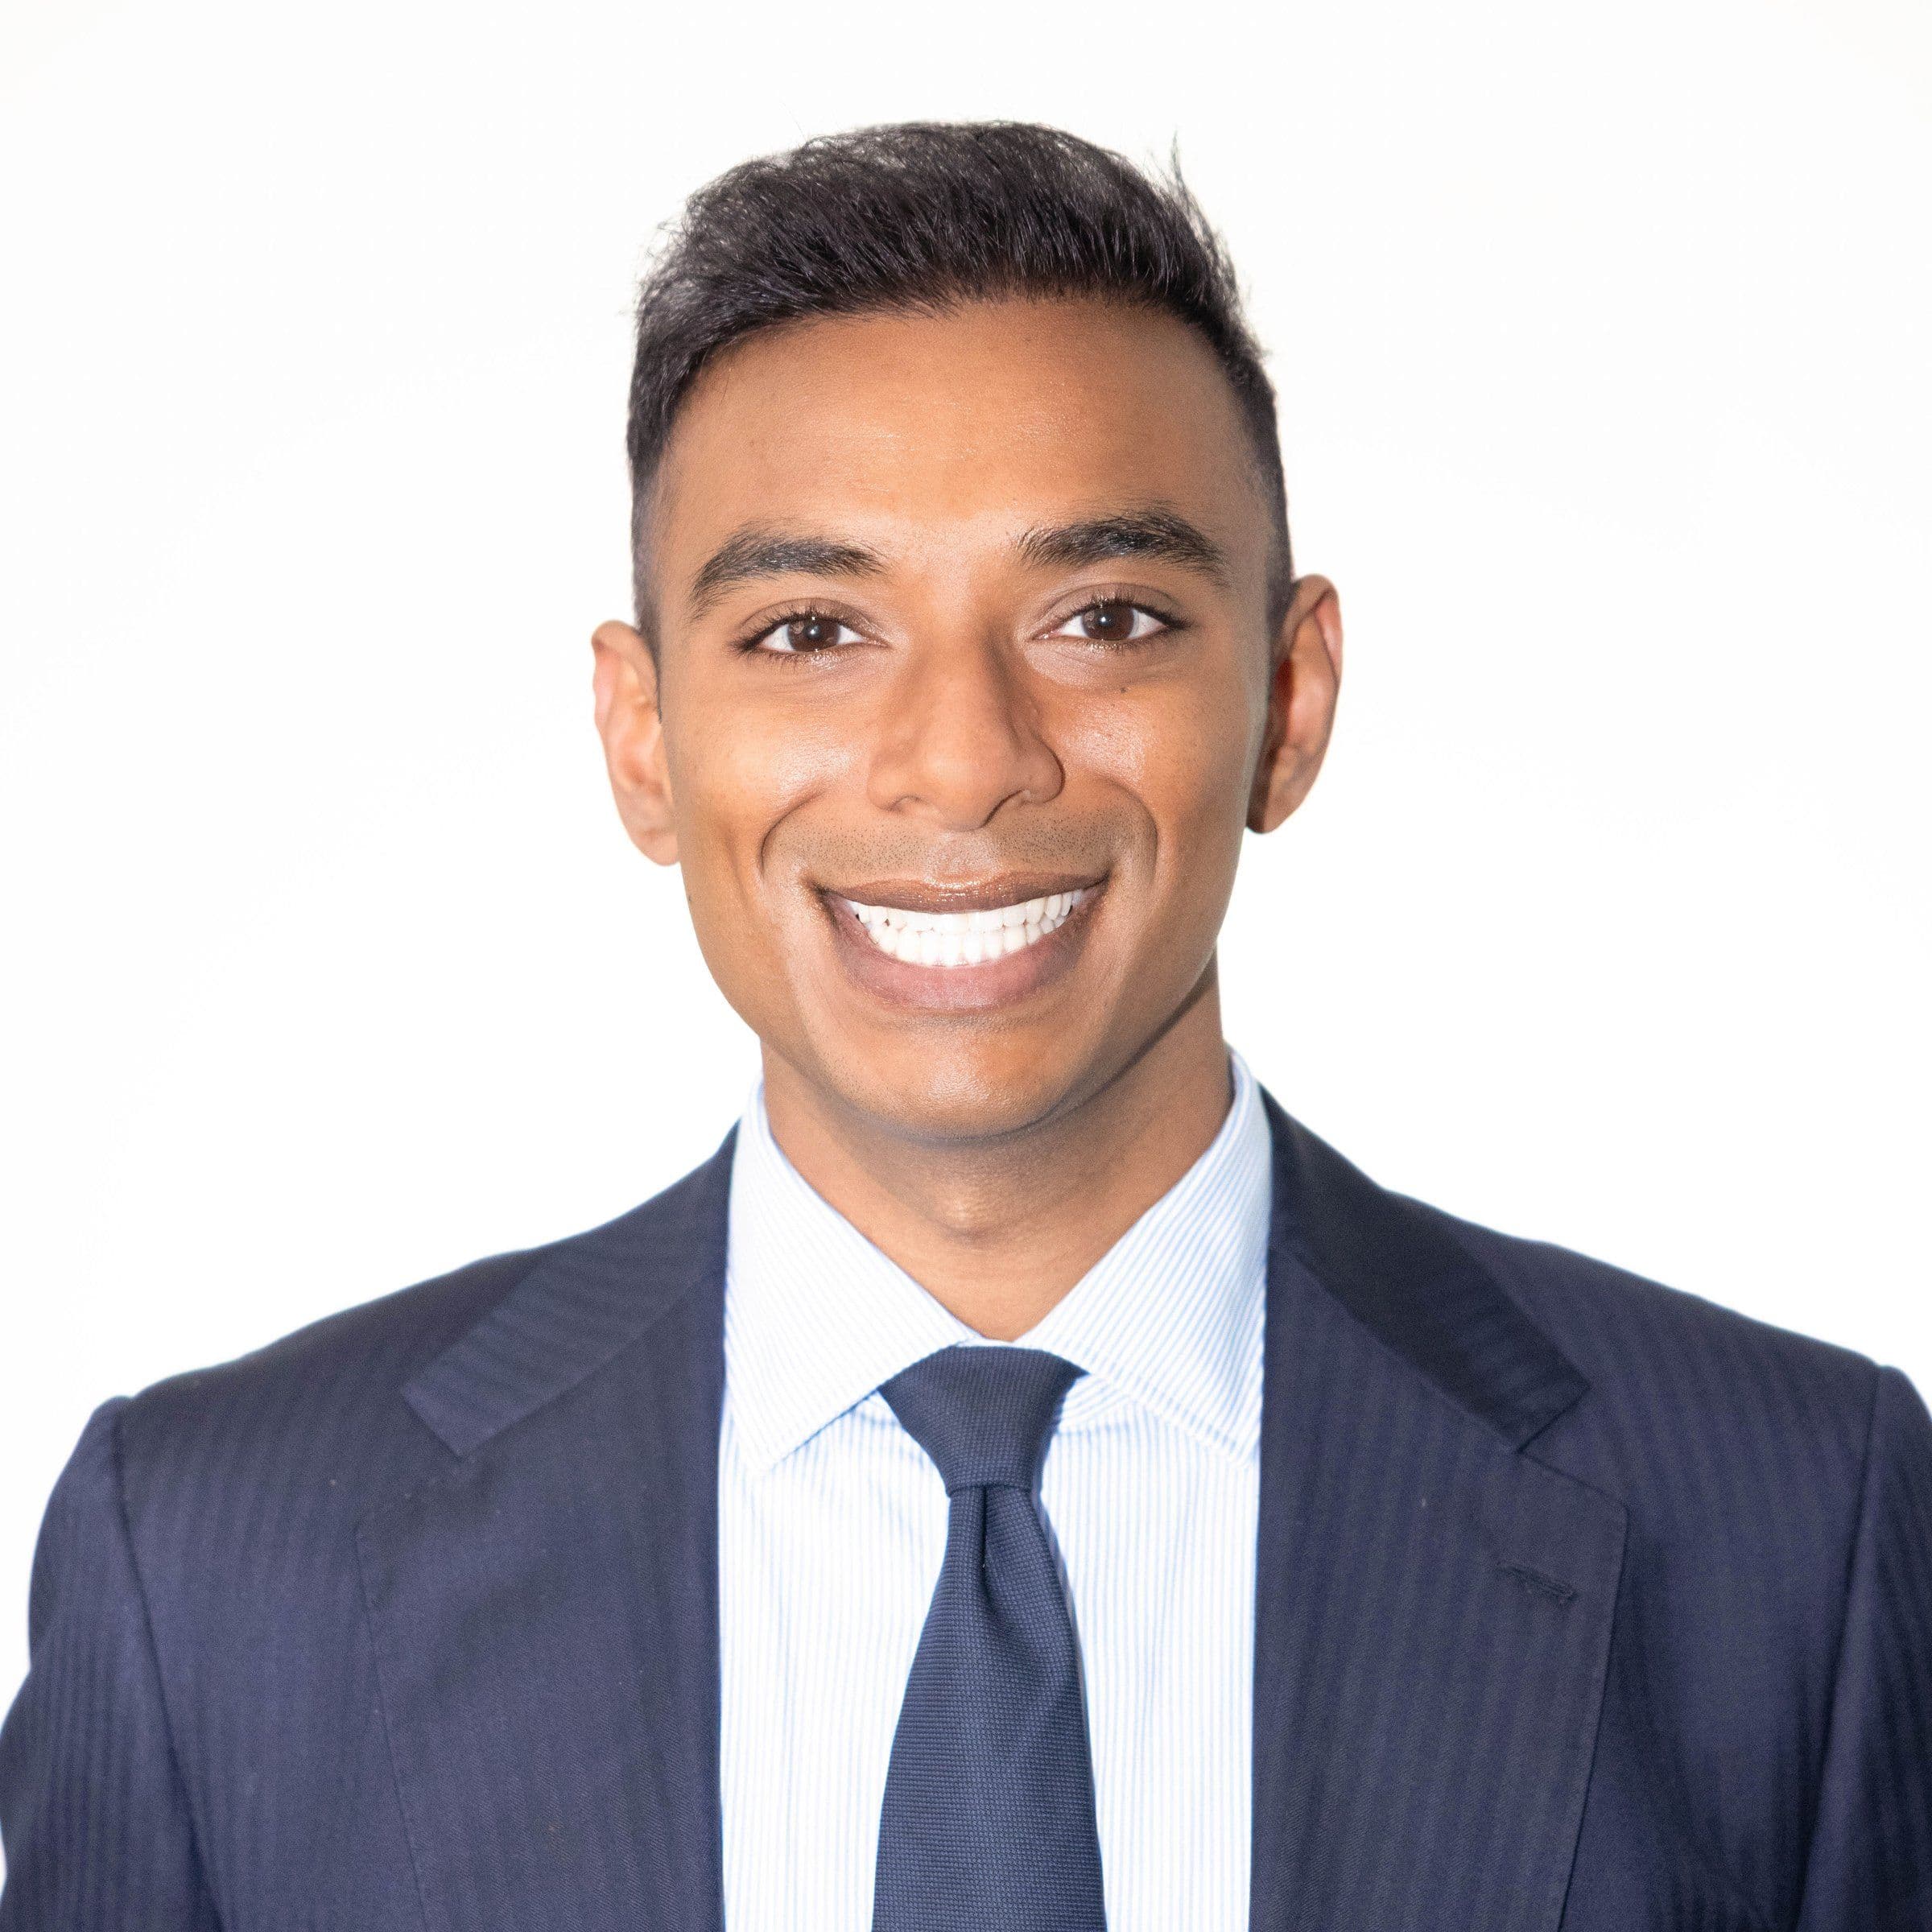
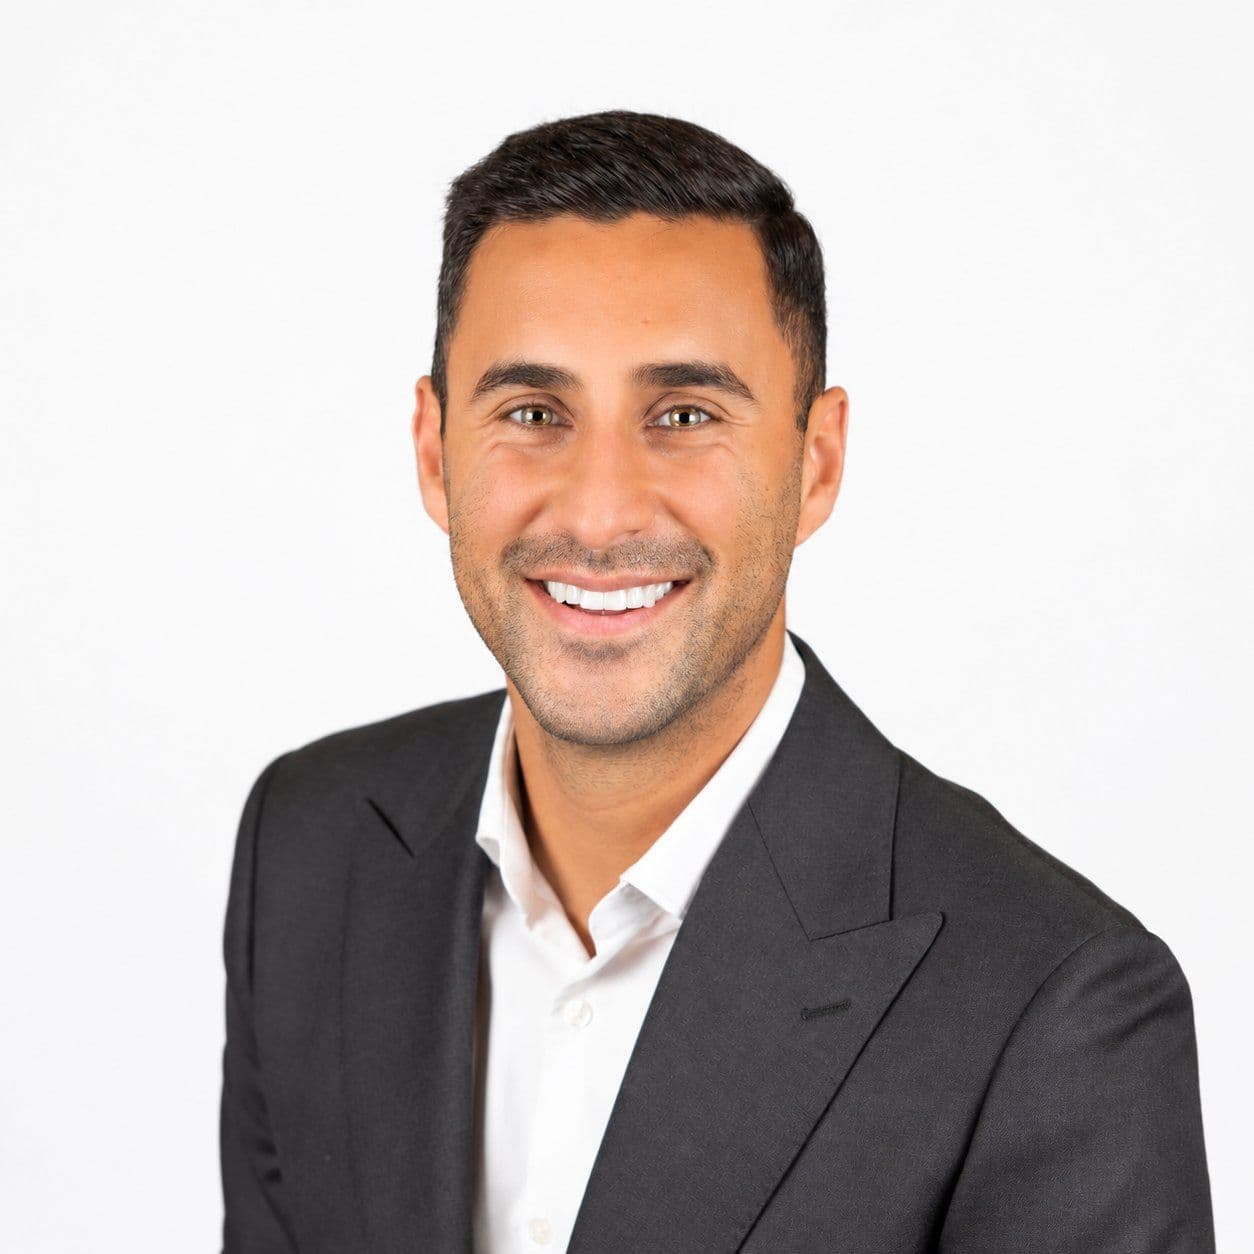
Speak with Tharun or Zain
Things to weigh up
Scheme criteria and places change
Government schemes can have limited places, participating lenders and price caps that change. Confirm eligibility before you set your search budget, not after.
New debt during approval
Taking on a car loan, buy now pay later account or new credit card before settlement can affect your approval. Talk to us before any new borrowing.
Genuine savings rules vary
Some lenders want savings held over a period, while others accept rental history or gifted funds. These policy differences can decide which lender fits.
Pre-approval is not final approval
Pre-approval is conditional. The lender still needs to assess the specific property and confirm nothing in your circumstances has changed.
Run the numbers
How much you need to buy: deposit, stamp duty, LMI and fees.
Cash you’ll need
$112,095
Loan $765,000 at 90% LVR
- Deposit
- $85,000
- Stamp duty
- $8,195
- LMI (estimate)
- $15,300
- Fees & conveyancing
- $3,600
Estimate only. Not an offer or approval of credit. Every lender assesses differently.
Questions first home buyers typically ask
Does my HECS-HELP debt affect how much I can borrow?
It can. Lenders generally factor compulsory repayments into their assessment, which may lower your borrowing capacity. The way lenders treat student debt varies and has been changing, so we check each lender's current approach before recommending one.
Can my parents help without giving us cash?
They may be able to act as guarantors, offering equity in their property as additional security for your loan. This can reduce or remove the need for lenders mortgage insurance. Guarantors take on real risk, so we explain the arrangement to everyone involved and recommend independent legal advice.
Does it matter to lenders whether I buy an apartment or a house?
It can. Some lenders apply tighter rules to small apartments, certain postcodes or high-density buildings, which may affect the deposit required or whether they will lend at all. We check how lenders view a property type before you commit, so the property and the finance line up.
What does a mortgage broker cost me?
In most cases, nothing. Lenders pay us a commission when your loan settles, and we disclose it in full in your Credit Proposal before you proceed. If a fee ever applies to your scenario, we tell you upfront, in writing.
You may also be considering
All services- Home LoansWe support clients through every stage of the purchase process, structuring lending solutions for owner-occupiers with a tailored, strategic approach.
- Investment LoansWe structure investment lending with the long game in mind – the right lender, the right structure and room to keep building.
- RefinancingWe review and restructure existing lending to secure more competitive rates, unlock equity, or consolidate debt – ensuring your finance continues to work in your favour.
Let’s map out your next move
Tell us where you are and where you want to be. A director will come back to you within one business day.
- Tharun Rameshbabu
- 0493 125 004tharun@terrainfp.com
- Zain Sumar
- 0494 503 777zain@terrainfp.com
- Office
- Level 3, 55 Pyrmont Bridge Road, Pyrmont NSW 2009